
IT distribution giant TD SYNNEX (NYSE:SNX) reported Q3 CY2026 results topping the market’s revenue expectations, with sales up 37.7% year on year to $21.56 billion. On top of that, next quarter’s revenue guidance ($22.2 billion at the midpoint) was surprisingly good and 13.5% above what analysts were expecting. Its non-GAAP profit of $5.68 per share was 20.8% above analysts’ consensus estimates.
Is now the time to buy TD SYNNEX? Find out by accessing our full research report, it’s free.
TD SYNNEX (SNX) Q3 CY2026 Highlights:
- Revenue: $21.56 billion vs analyst estimates of $19 billion (37.7% year-on-year growth, 13.5% beat)
- Adjusted EPS: $5.68 vs analyst estimates of $4.70 (20.8% beat)
- Revenue Guidance for Q4 CY2026 is $22.2 billion at the midpoint, above analyst estimates of $19.57 billion
- Adjusted EPS guidance for Q4 CY2026 is $5.90 at the midpoint, above analyst estimates of $4.87
- Operating Margin: 3%, in line with the same quarter last year
- Free Cash Flow was -$975.6 million, down from $213.9 million in the same quarter last year
- Market Capitalization: $23.02 billion
"We delivered another record quarter, with Distribution and Hyve both performing above our expectations and growing above market," said Patrick Zammit, CEO of TD SYNNEX. “Enterprise AI adoption is progressing toward broader production deployments. Data center modernization remains a priority as organizations prepare for next-generation infrastructure requirements, while AI is driving new security, governance, and compliance requirements across technology environments. We believe these trends expand our opportunities across Distribution and Hyve and support our confidence in our long-term growth potential.”
Company Overview
Serving as the crucial middleman in the technology supply chain, TD SYNNEX (NYSE:SNX) is a global technology distributor that connects thousands of IT manufacturers with resellers, helping businesses access hardware, software, and technology solutions.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
With $75.67 billion in revenue over the past 12 months, TD SYNNEX is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices.
As you can see below, TD SYNNEX’s sales grew at an incredible 27.9% compounded annual growth rate over the last five years. This is a great starting point for our analysis because it shows TD SYNNEX’s demand was higher than many business services companies.
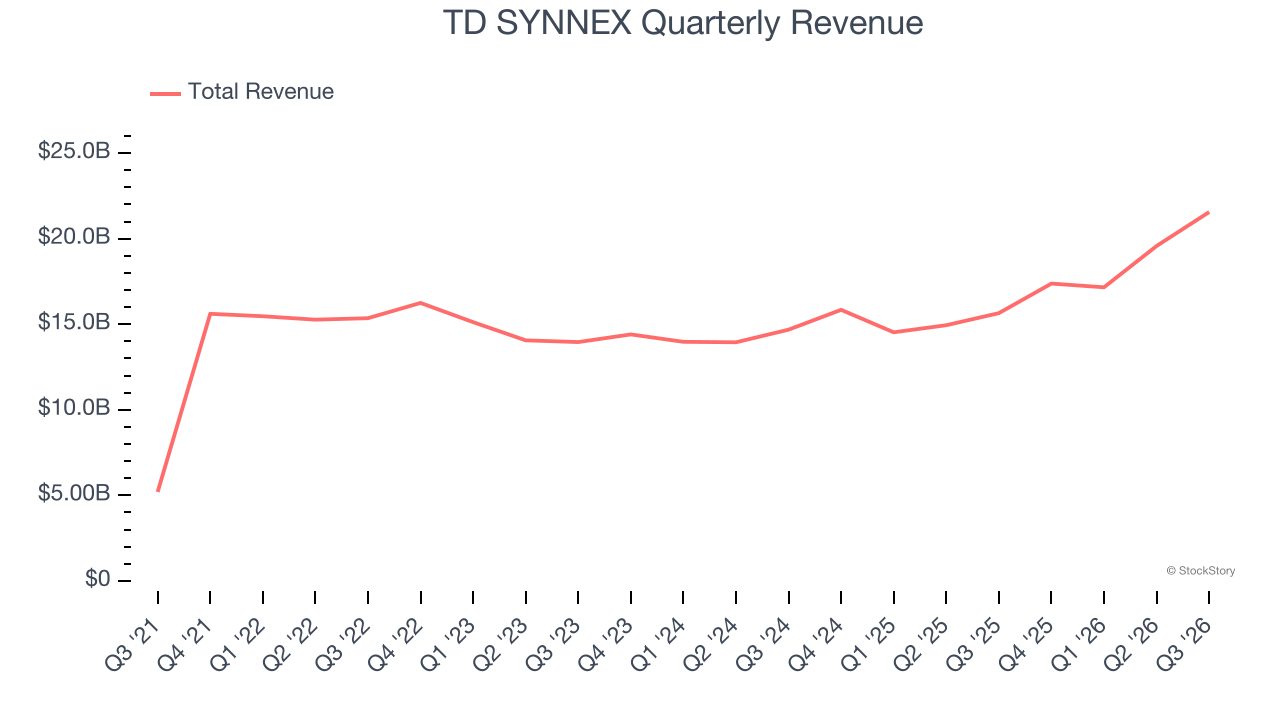
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. TD SYNNEX’s annualized revenue growth of 15.2% over the last two years is below its five-year trend, but we still think the results suggest healthy demand. 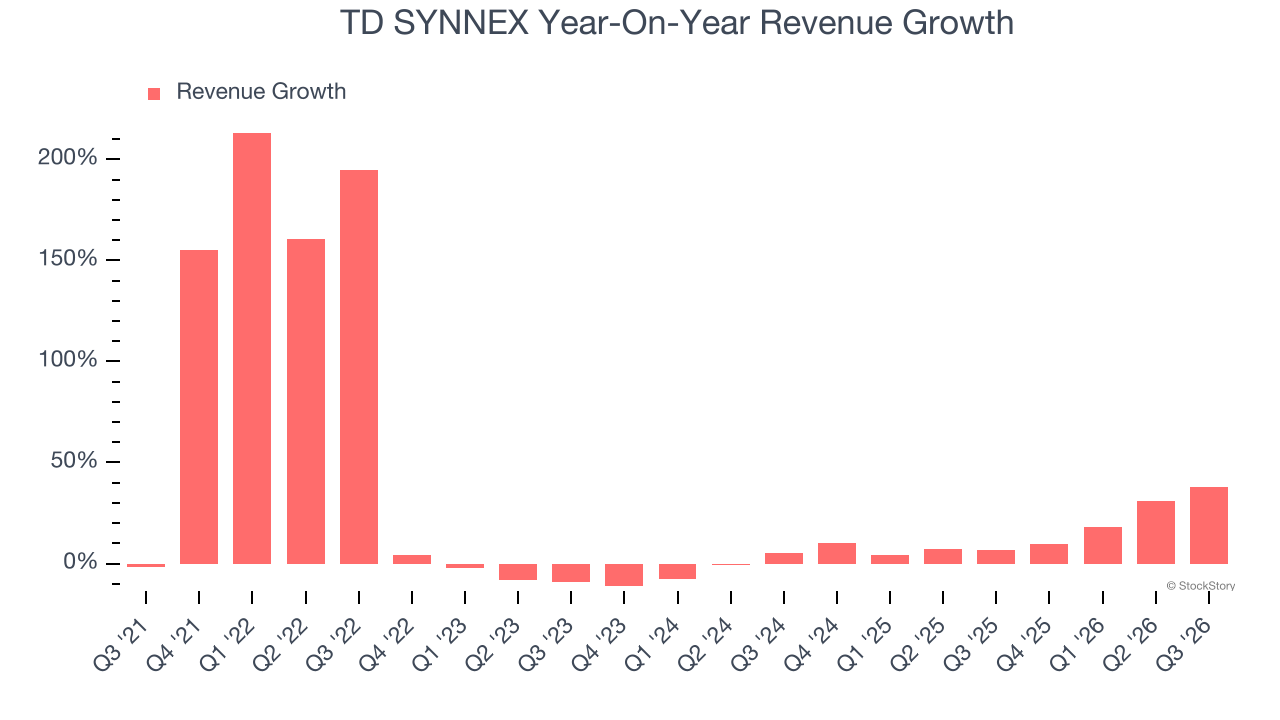
This quarter, TD SYNNEX reported wonderful year-on-year revenue growth of 37.7%, and its $21.56 billion of revenue exceeded Wall Street’s estimates by 13.5%. Company management is currently guiding for a 27.7% year-on-year increase in sales next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 5.1% over the next 12 months, a deceleration versus the last two years. We still think its growth trajectory is satisfactory given its scale and implies the market is baking in success for its products and services.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Adjusted Operating Margin
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
TD SYNNEX’s adjusted operating margin has more or less stayed the same over the last 12 months , averaging 2.9% over the last five years. This profitability was lousy for a business services business and caused by its suboptimal cost structure.
Analyzing the trend in its profitability, TD SYNNEX’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
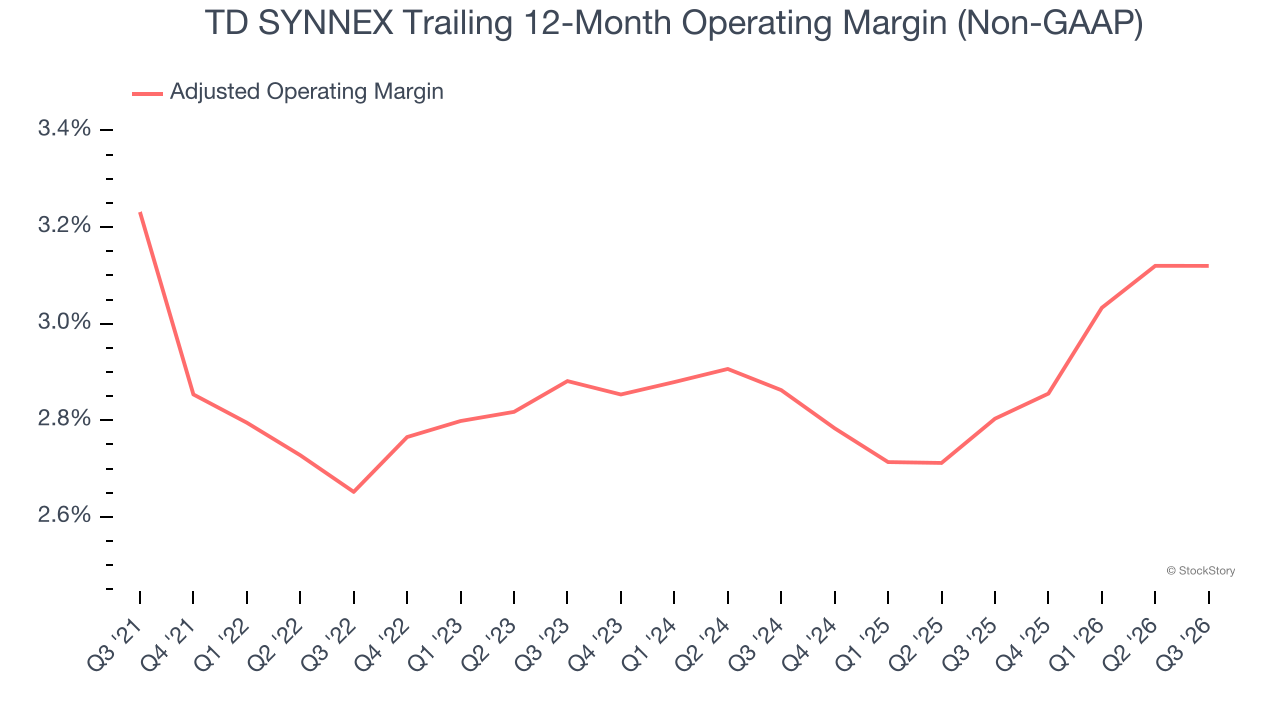
In Q3, TD SYNNEX generated an adjusted operating margin profit margin of 3.1%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
TD SYNNEX’s EPS grew at a remarkable 11% compounded annual growth rate over the last five years. However, this performance was lower than its 27.9% annualized revenue growth, telling us the company became less profitable on a per-share basis as it expanded.
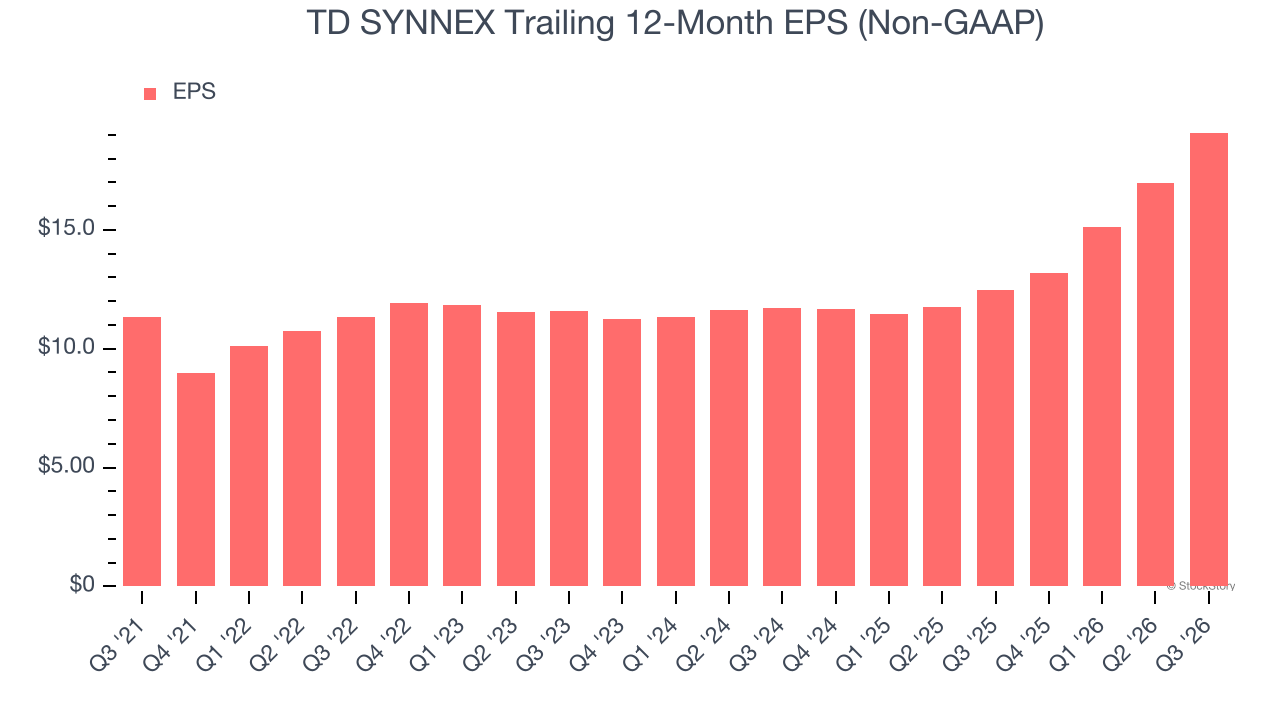
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For TD SYNNEX, its two-year annual EPS growth of 27.7% was higher than its five-year trend. We love it when earnings growth accelerates, especially when it accelerates off an already high base.
In Q3, TD SYNNEX reported adjusted EPS of $5.68, up from $3.58 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects TD SYNNEX’s full-year EPS to grow 10.3% from $19.09 to $21.06.
Key Takeaways from TD SYNNEX’s Q3 Results
It was good to see TD SYNNEX beat analysts’ EPS expectations this quarter. We were also excited its EPS guidance for next quarter outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a good print with some key areas of upside. The market seemed to be hoping for more, and the stock traded down 3.2% to $278.54 immediately following the results.
So do we think TD SYNNEX is an attractive buy at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).