

Earnings results often indicate what direction a company will take in the months ahead. With Q2 behind us, let’s have a look at Crocs (NASDAQ:CROX) and its peers.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Footwear companies design, manufacture, and market shoes across athletic, casual, and luxury segments. Tailwinds include the global athleisure trend, growing health and fitness awareness driving sneaker demand, and expanding direct-to-consumer digital channels that improve brand control and margins. However, headwinds are notable: the industry faces intense competition and brand-switching behavior, heavy marketing spend requirements to maintain relevance, and exposure to volatile raw material and freight costs. Tariff risk from concentrated overseas manufacturing, primarily in Asia, remains a persistent concern. Additionally, inventory management is challenging given seasonal and trend-driven demand, with markdowns eroding profitability when styles miss consumer expectations.
The 7 consumer discretionary - footwear stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 1.3%.
While some consumer discretionary - footwear stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 3.8% since the latest earnings results.
Crocs (NASDAQ:CROX)
Founded in 2002, Crocs (NASDAQ:CROX) sells casual footwear and is known for its iconic clog shoe.
Crocs reported revenues of $1.18 billion, up 2.6% year on year. This print exceeded analysts’ expectations by 2.7%. Despite the top-line beat, it was still a mixed quarter for the company with a beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations.
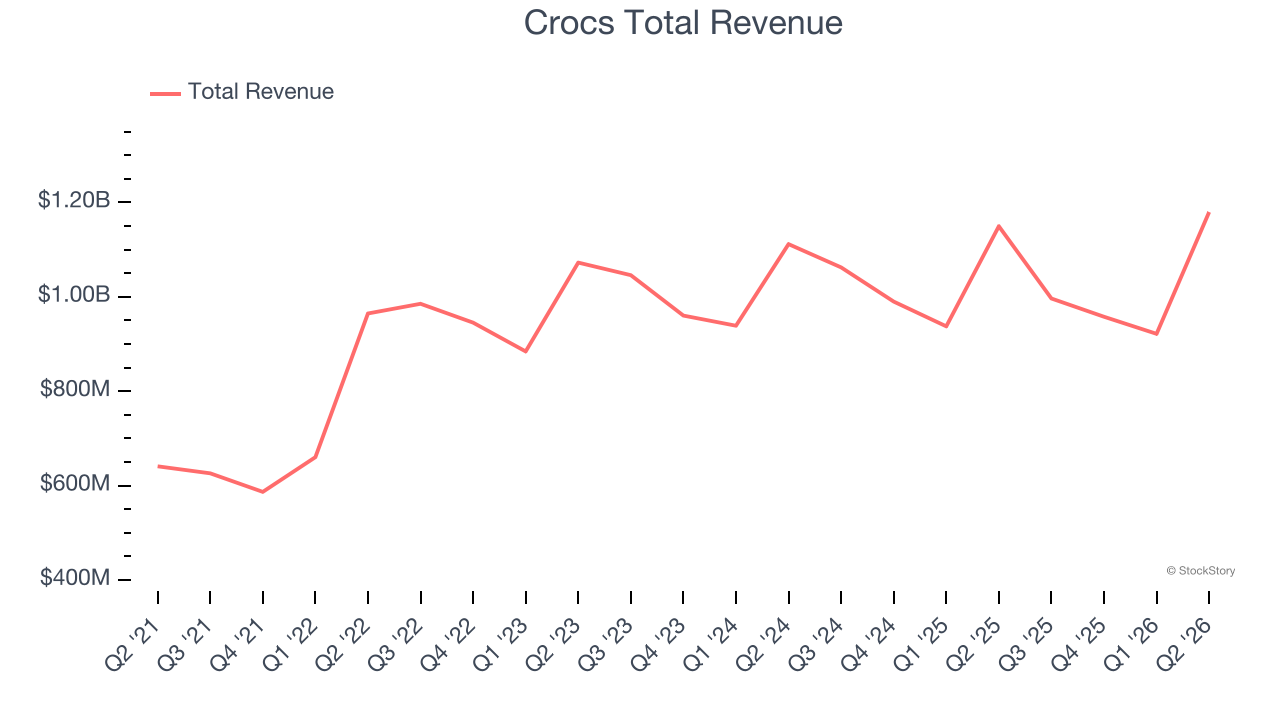
The market seems disappointed with the results as the stock is down 6.8% since reporting and currently trades at $124.38.
Is now the time to buy Crocs? Access our full analysis of the earnings results here, it’s free.
Best Q2: Steven Madden (NASDAQ:SHOO)
As seen in the infamous Wolf of Wall Street movie, Steven Madden (NASDAQ:SHOO) is a fashion brand famous for its trendy and innovative footwear, appealing to a young and style-conscious audience.
Steven Madden reported revenues of $665.9 million, up 19.1% year on year, outperforming analysts’ expectations by 4.8%. The business had an exceptional quarter with a beat of analysts’ EPS estimates.
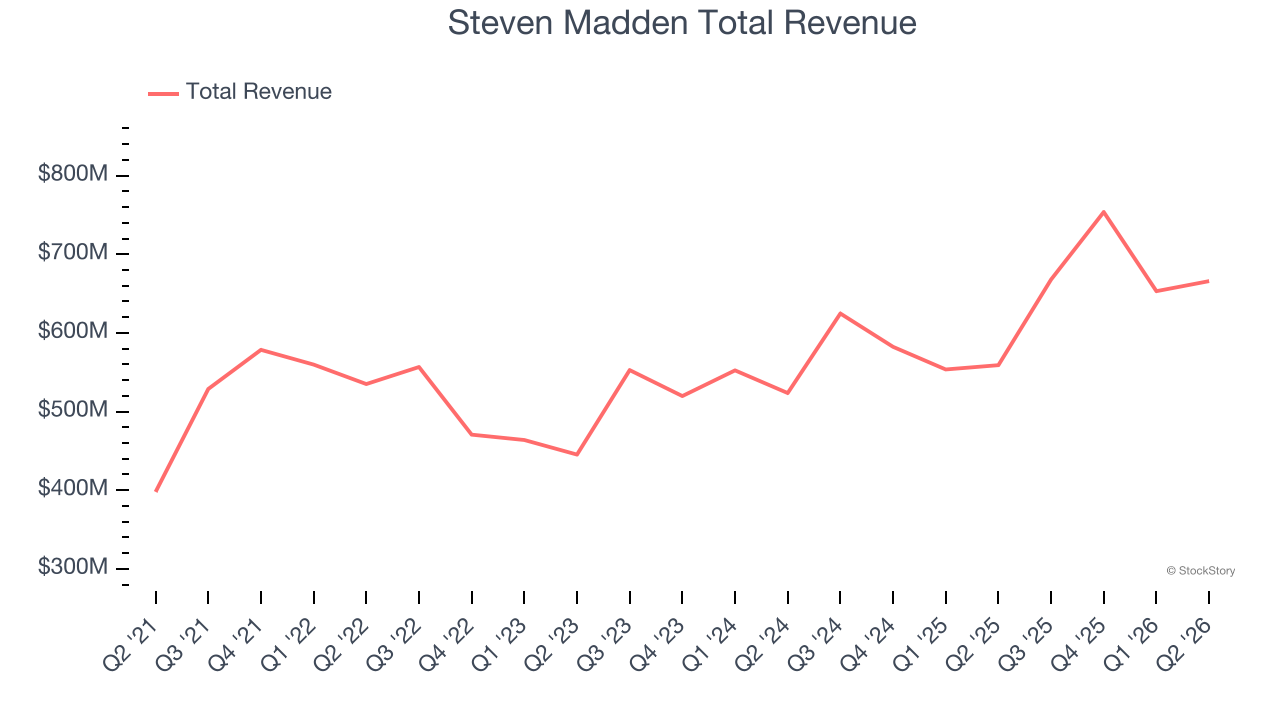
Steven Madden delivered the biggest analyst estimate beat and fastest revenue growth among its peers. However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $43.39.
Is now the time to buy Steven Madden? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Caleres (NYSE:CAL)
The owner of Dr. Scholl's, Caleres (NYSE:CAL) is a footwear company offering a range of styles.
Caleres reported revenues of $695.5 million, up 5.6% year on year, falling short of analysts’ expectations by 1%. It was a slower quarter as it posted EPS guidance for next quarter missing analysts’ expectations significantly and full-year EPS guidance missing analysts’ expectations.
Caleres delivered the weakest performance against analyst estimates in the group. Interestingly, the stock is up 2.9% since the results and currently trades at $12.38.
Read our full analysis of Caleres’s results here.
Deckers (NYSE:DECK)
Established in 1973, Deckers (NYSE:DECK) is a footwear and apparel conglomerate with a portfolio of lifestyle and performance brands.
Deckers reported revenues of $1.02 billion, up 5.7% year on year. This result was in line with analysts’ expectations. More broadly, it was a mixed quarter as it also recorded a beat of analysts’ EPS estimates but full-year revenue guidance meeting analysts’ expectations.
Deckers had the weakest full-year guidance update of the whole group. The stock is down 18.1% since reporting and currently trades at $78.80.
Read our full, actionable report on Deckers here, it’s free.
Wolverine Worldwide (NYSE:WWW)
Founded in 1883, Wolverine Worldwide (NYSE:WWW) is a global footwear company with a diverse portfolio of brands including Merrell, Hush Puppies, and Saucony.
Wolverine Worldwide reported revenues of $506.4 million, up 6.8% year on year. This number topped analysts’ expectations by 0.9%. It was a satisfactory quarter as it also produced full-year EPS guidance topping analysts’ expectations.
Wolverine Worldwide pulled off the highest full-year guidance raise among its peers. The stock is up 5.8% since reporting and currently trades at $19.11.
Read our full, actionable report on Wolverine Worldwide here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.