

The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how semiconductor manufacturing stocks fared in Q2, starting with Teradyne (NASDAQ:TER).
The semiconductor industry is driven by demand for advanced electronic products like smartphones, PCs, servers, and data storage. The need for technologies like artificial intelligence, 5G networks, and smart cars is also creating the next wave of growth for the industry. Keeping up with this dynamism requires new tools that can design, fabricate, and test chips at ever smaller sizes and more complex architectures, creating a dire need for semiconductor capital manufacturing equipment.
The 14 semiconductor manufacturing stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.5% while next quarter’s revenue guidance was 6.5% above.
Thankfully, share prices of the companies have been resilient as they are up 7.2% on average since the latest earnings results.
Teradyne (NASDAQ:TER)
Sporting most major chip manufacturers as its customers, Teradyne (NASDAQ:TER) is a US-based supplier of automated test equipment for semiconductors as well as other technologies and devices.
Teradyne reported revenues of $1.33 billion, up 104% year on year. This print exceeded analysts’ expectations by 9.3%. Overall, it was a stunning quarter for the company with a beat of analysts’ EPS estimates and an impressive beat of analysts’ operating income estimates.
"Our strategy to capture test and robotics opportunities from wafer to AI data center has driven another record quarter. This strength became evident in the year-on-year market expansion for all three of our business groups,” said Teradyne CEO Greg Smith.
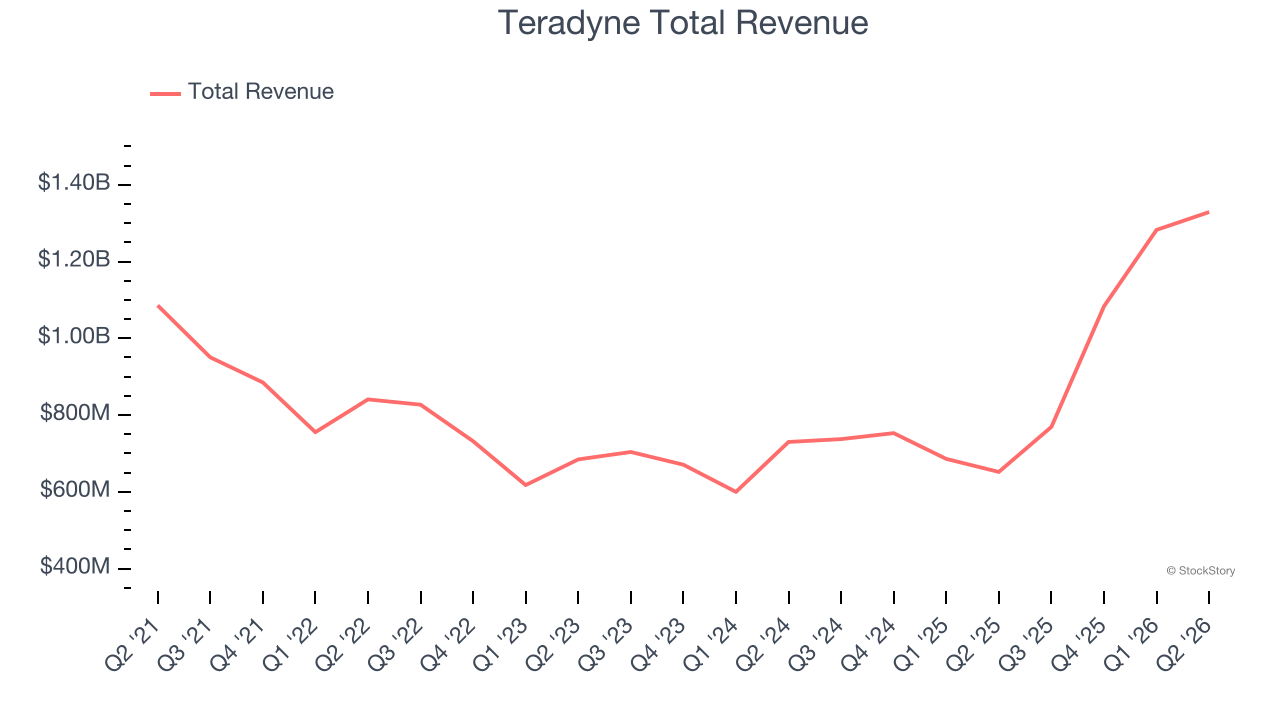
Teradyne scored the biggest analyst estimate beat and highest guidance raise in the group. Unsurprisingly, the stock is up 20.8% since reporting and currently trades at $387.50.
Is now the time to buy Teradyne? Access our full analysis of the earnings results here, it’s free.
Best Q2: Kulicke and Soffa (NASDAQ:KLIC)
Headquartered in Singapore, Kulicke & Soffa (NASDAQ: KLIC) is a provider of production equipment and tools used to assemble semiconductor devices
Kulicke and Soffa reported revenues of $330.4 million, up 123% year on year, outperforming analysts’ expectations by 5.7%. The business had a stunning quarter with a significant improvement in its inventory levels and a beat of analysts’ EPS estimates.
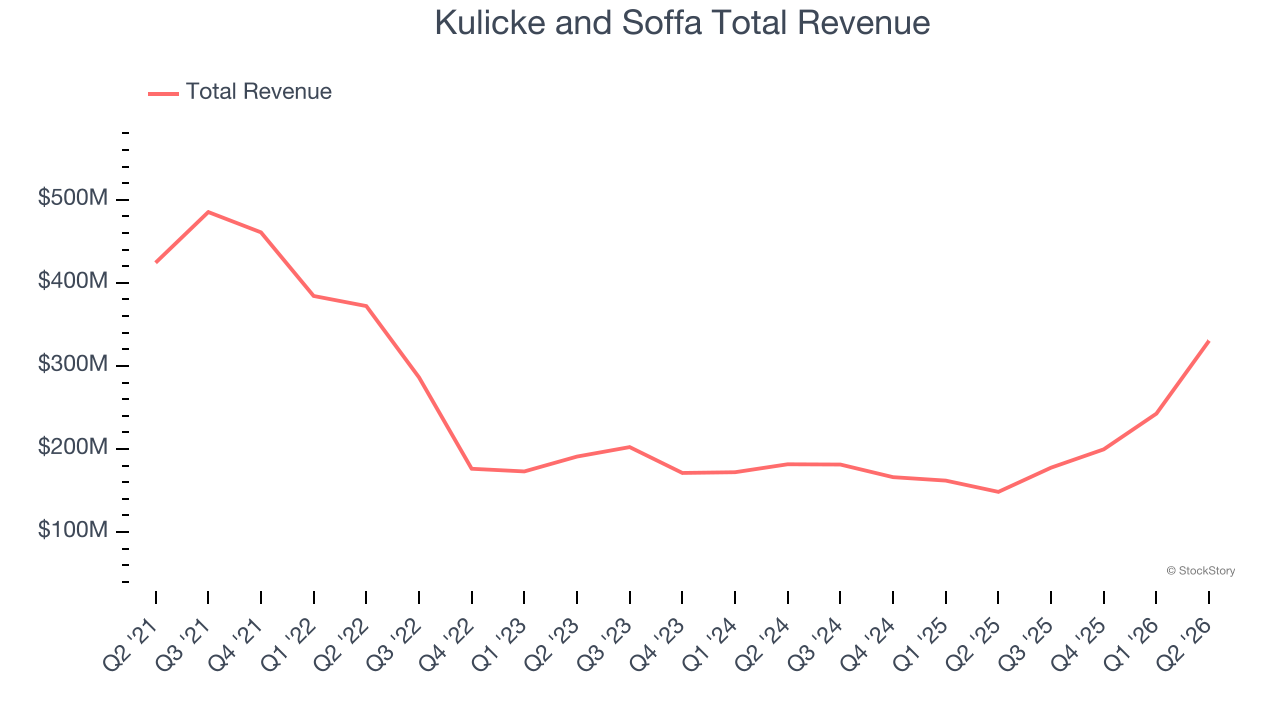
Kulicke and Soffa achieved the fastest revenue growth of the whole group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 3.2% since reporting. It currently trades at $90.86.
Is now the time to buy Kulicke and Soffa? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: KLA Corporation (NASDAQ:KLAC)
Formed by the 1997 merger of the two leading semiconductor yield management companies, KLA Corporation (NASDAQ:KLAC) is the leading supplier of equipment used to measure and inspect semiconductor chips.
KLA Corporation reported revenues of $3.66 billion, up 15.2% year on year, exceeding analysts’ expectations by 1.3%. It may have had the worst quarter among its peers, but its results were still good as it also locked in a beat of analysts’ EPS estimates and a decent beat of analysts’ operating income estimates.
As expected, the stock is down 1.5% since the results and currently trades at $188.03.
Read our full analysis of KLA Corporation’s results here.
Entegris (NASDAQ:ENTG)
With fabs representing the company’s largest customer type, Entegris (NASDAQ:ENTG) supplies products that purify, protect, and generally ensure the integrity of raw materials needed for advanced semiconductor manufacturing.
Entegris reported revenues of $883.2 million, up 11.5% year on year. This print beat analysts’ expectations by 5.5%. Overall, it was an exceptional quarter as it also produced a beat of analysts’ EPS estimates and an impressive beat of analysts’ operating income estimates.
The stock is up 19.8% since reporting and currently trades at $149.97.
Read our full, actionable report on Entegris here, it’s free.
Amtech (NASDAQ:ASYS)
Focusing on the silicon carbide and power semiconductor sectors, Amtech Systems (NASDAQ:ASYS) produces the machinery and related chemicals needed for manufacturing semiconductors.
Amtech reported revenues of $22.38 million, up 14.5% year on year. This number topped analysts’ expectations by 4.1%. It was an exceptional quarter as it also logged a beat of analysts’ EPS estimates and an impressive beat of analysts’ operating income estimates.
The stock is down 5.2% since reporting and currently trades at $15.19.
Read our full, actionable report on Amtech here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Strong Momentum Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.