

As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the industrial distributors industry, including Boise Cascade (NYSE:BCC) and its peers.
Supply chain and inventory management are themes that grew in focus after COVID wreaked havoc on the global movement of raw materials and components. Distributors that boast a reliable selection of products–everything from hardhats and fasteners for jet engines to ceiling systems–and quickly deliver goods to customers can benefit from this theme. While e-commerce hasn’t disrupted industrial distribution as much as consumer retail, it is still a real threat, forcing investment in omnichannel capabilities to better interact with customers. Additionally, distributors are at the whim of economic cycles that impact the capital spending and construction projects that can juice demand.
The 24 industrial distributors stocks we track reported a very strong Q2. As a group, revenues beat analysts’ consensus estimates by 3.7%.
While some industrial distributors stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 1.8% since the latest earnings results.
Boise Cascade (NYSE:BCC)
Formed through the merger of two lumber companies, Boise Cascade Company (NYSE:BCC) manufactures and distributes wood products and other building materials.
Boise Cascade reported revenues of $1.83 billion, up 5.2% year on year. This print exceeded analysts’ expectations by 3.4%. Overall, it was a stunning quarter for the company with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
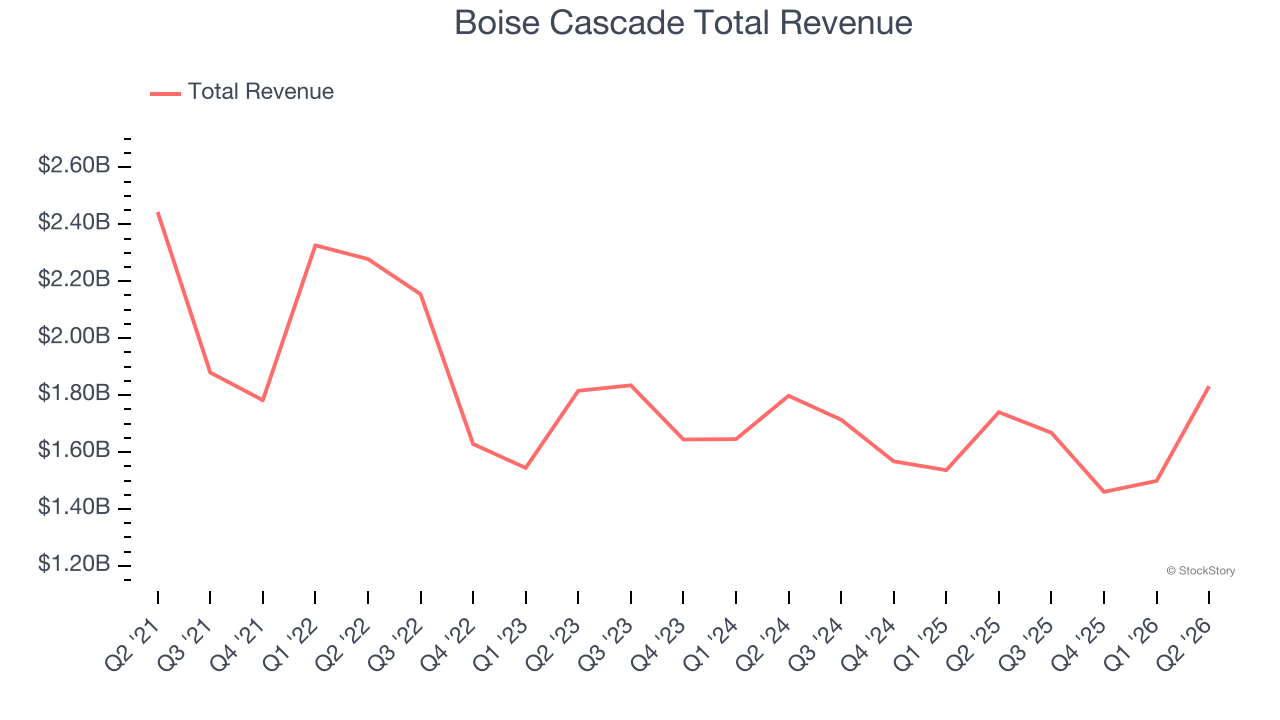
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 6.3% since reporting and currently trades at $77.77.
Is now the time to buy Boise Cascade? Access our full analysis of the earnings results here, it’s free.
Best Q2: Richardson Electronics (NASDAQ:RELL)
Founded in 1947, Richardson Electronics (NASDAQ:RELL) is a distributor of power grid and microwave tubes as well as consumables related to those products.
Richardson Electronics reported revenues of $66.2 million, up 27.6% year on year, outperforming analysts’ expectations by 19.6%. The business had an incredible quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
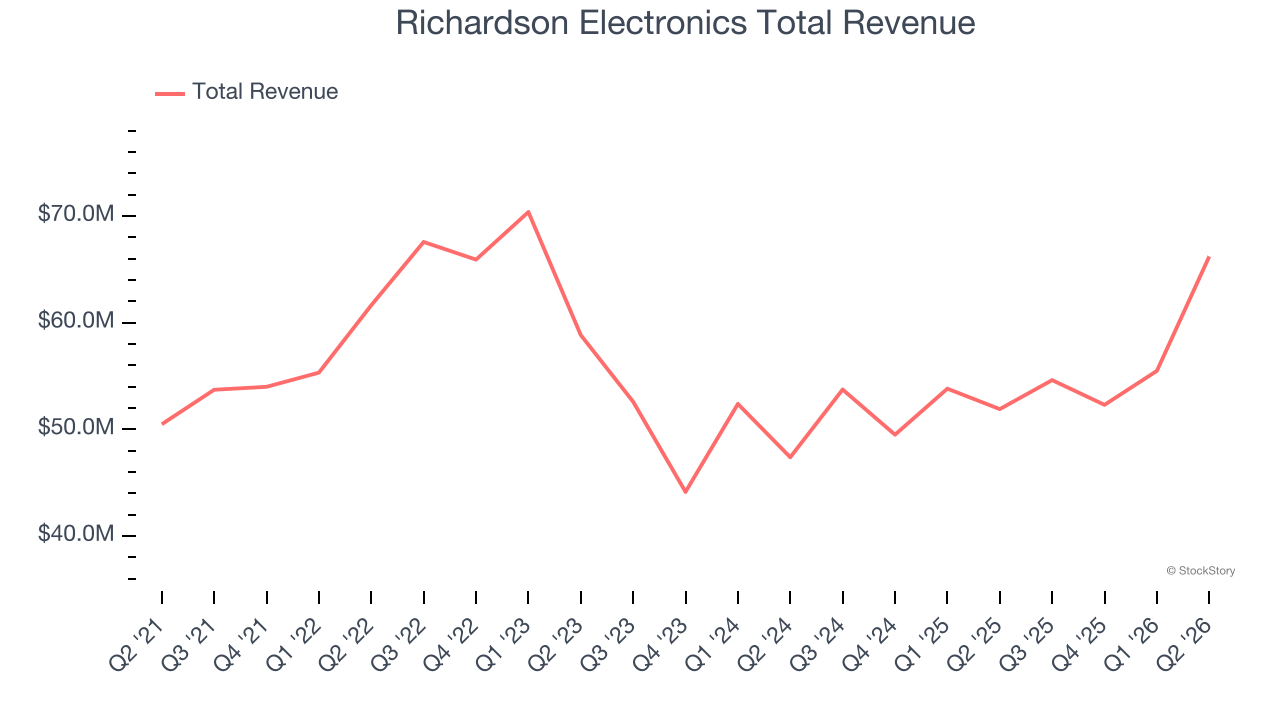
Richardson Electronics scored the biggest analyst estimate beat among its peers. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 6.2% since reporting. It currently trades at $16.90.
Is now the time to buy Richardson Electronics? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Watsco (NYSE:WSO)
Originally a manufacturing company, Watsco (NYSE:WSO) today only distributes air conditioning, heating, and refrigeration equipment, as well as related parts and supplies.
Watsco reported revenues of $2.10 billion, up 2.1% year on year, falling short of analysts’ expectations by 1.9%. It was a disappointing quarter as it posted a significant miss of analysts’ EPS estimates.
As expected, the stock is down 11.4% since the results and currently trades at $325.47.
Read our full analysis of Watsco’s results here.
United Rentals (NYSE:URI)
Owning the largest rental fleet in the world, United Rentals (NYSE:URI) provides equipment rental and related services to construction, industrial, and infrastructure industries.
United Rentals reported revenues of $4.41 billion, up 11.8% year on year. This number beat analysts’ expectations by 4.9%. Overall, it was a stunning quarter as it also recorded an impressive beat of analysts’ EBITDA estimates and full-year EBITDA guidance exceeding analysts’ expectations.
The stock is flat since reporting and currently trades at $1,033.
Read our full, actionable report on United Rentals here, it’s free.
Transcat (NASDAQ:TRNS)
Serving the pharmaceutical, industrial manufacturing, energy, and chemical process industries, Transcat (NASDAQ:TRNS) provides measurement instruments and supplies.
Transcat reported revenues of $92.95 million, up 21.6% year on year. This result surpassed analysts’ expectations by 7.4%. It was an incredible quarter as it also put up a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
The stock is down 3.2% since reporting and currently trades at $88.97.
Read our full, actionable report on Transcat here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.