

Over the past six months, Genesis Energy’s shares (currently trading at $14.67) have posted a disappointing 18.2% loss, well below the S&P 500’s 18.4% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Genesis Energy, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Genesis Energy Will Underperform?
Even with the cheaper entry price, we’re cautious about Genesis Energy. Here are three reasons we avoid GEL, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
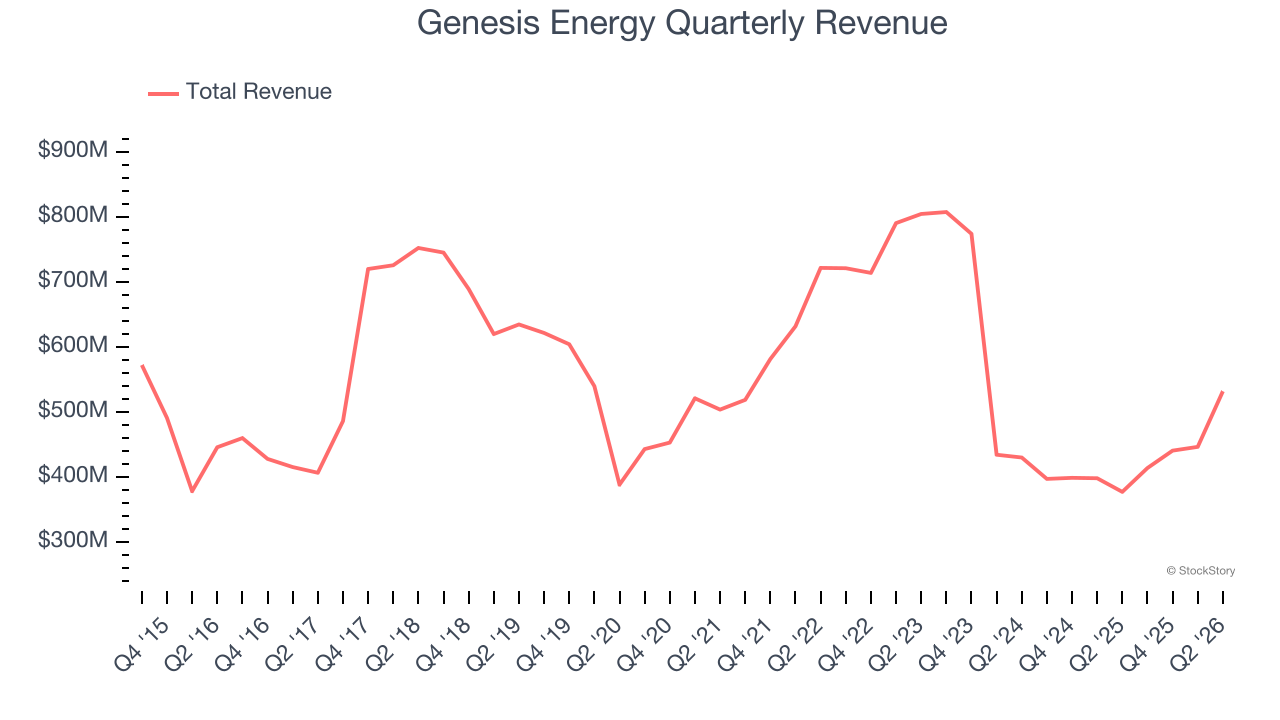
Cyclical sectors like Energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Unfortunately, Genesis Energy struggled to consistently increase demand as its $1.83 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of poor business quality.
2. Low Gross Margin Reveals Weak Structural Profitability
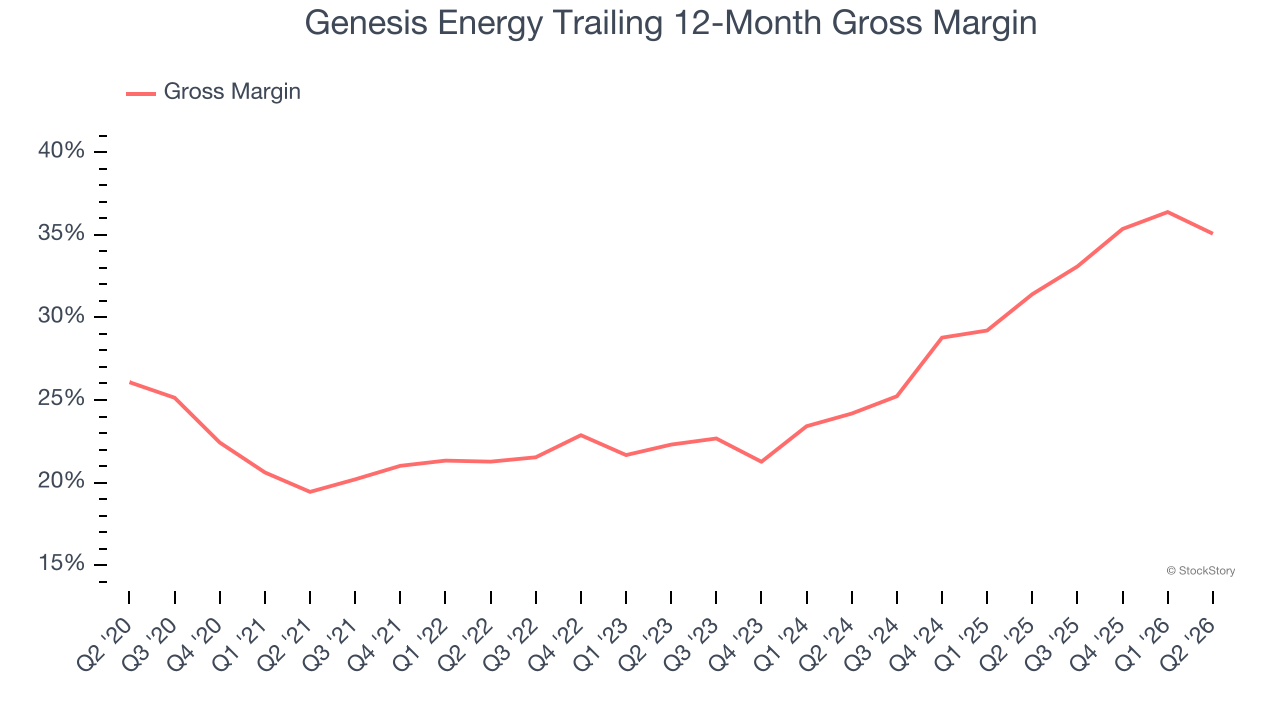
While energy gross margins can be distorted by commodity prices, hedging, and short-term cost swings, sustained margins across a full cycle reflect a producer’s underlying asset quality, infrastructure position, and cost structure.
Genesis Energy, which averaged 25.8% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. High Debt Levels Increase Risk
Debt is a tool that can boost company returns but presents risks if used irresponsibly. As long-term investors, we aim to avoid companies taking excessive advantage of this instrument because it could lead to insolvency.
Genesis Energy’s $3.10 billion of debt exceeds the $44.24 million of cash on its balance sheet. Furthermore, its 5× net-debt-to-EBITDA ratio (based on its EBITDA of $602.1 million over the last 12 months) shows the company is overleveraged.
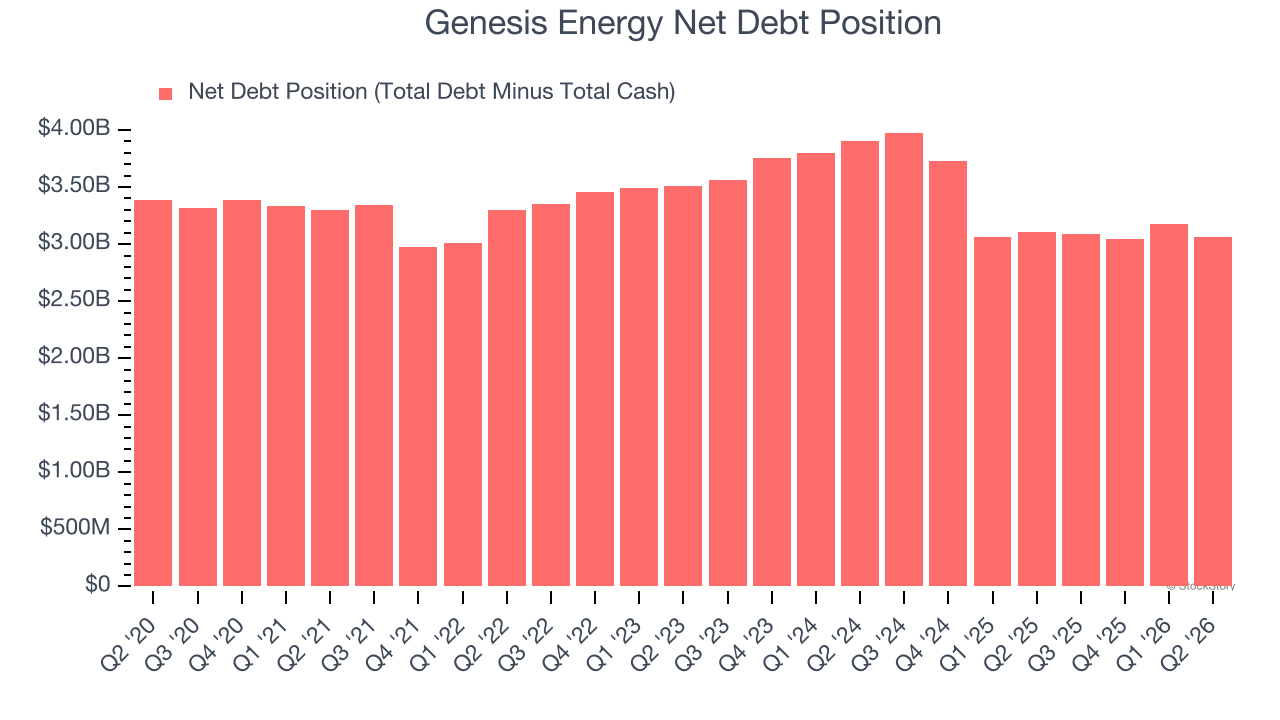
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Genesis Energy could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Genesis Energy can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
We see the value of companies helping consumers, but in the case of Genesis Energy, we’re out. After the recent drawdown, the stock trades at 8.4× forward EV-to-EBITDA (or $14.67 per share). This multiple tells us a lot of good news is priced in - you can find more timely opportunities elsewhere. We’d suggest looking at one of our top digital advertising picks.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.