

Even though First Financial Bankshares (currently trading at $31.93 per share) has gained 8% over the last six months, it has lagged the S&P 500’s 18.4% return during that period. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is there a buying opportunity in First Financial Bankshares, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is First Financial Bankshares Not Exciting?
We’re sitting this one out for now. Here are three reasons you should be careful with FFIN, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities.
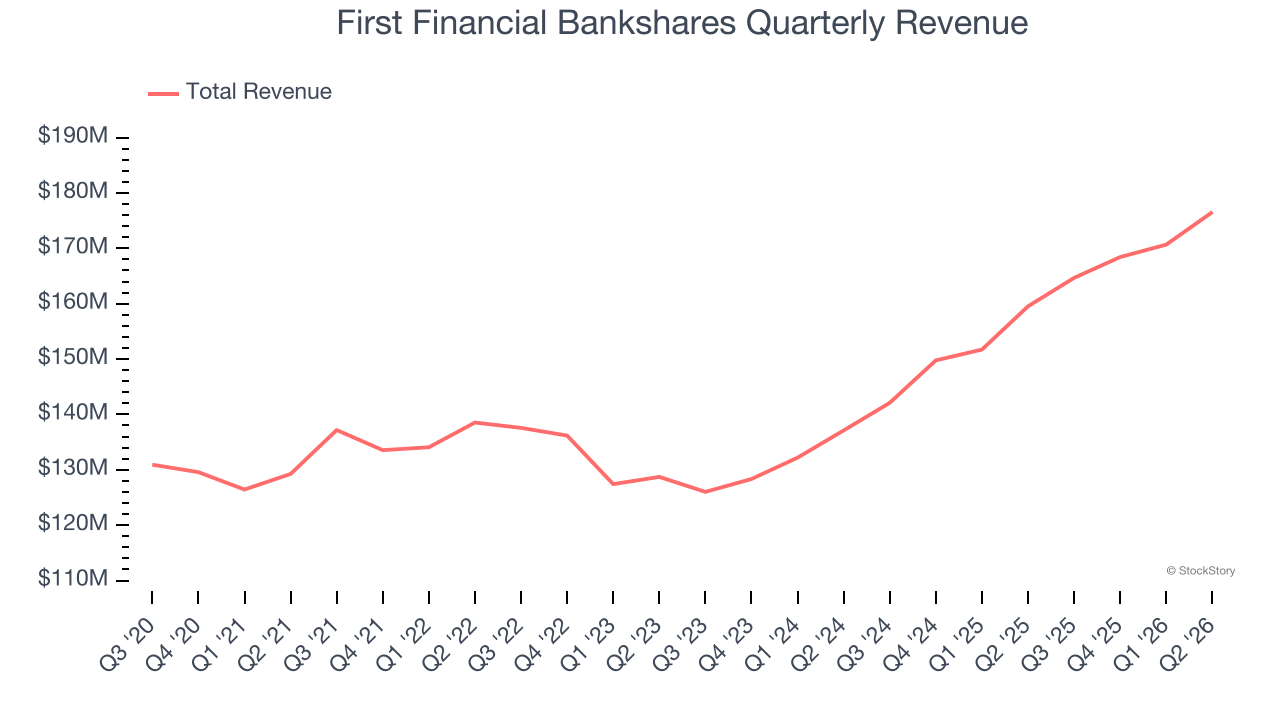
Regrettably, First Financial Bankshares’s revenue grew at a sluggish 5.7% compounded annual growth rate over the last five years. This fell short of our benchmark for the banking sector.
2. Net Interest Income Points to Soft Demand
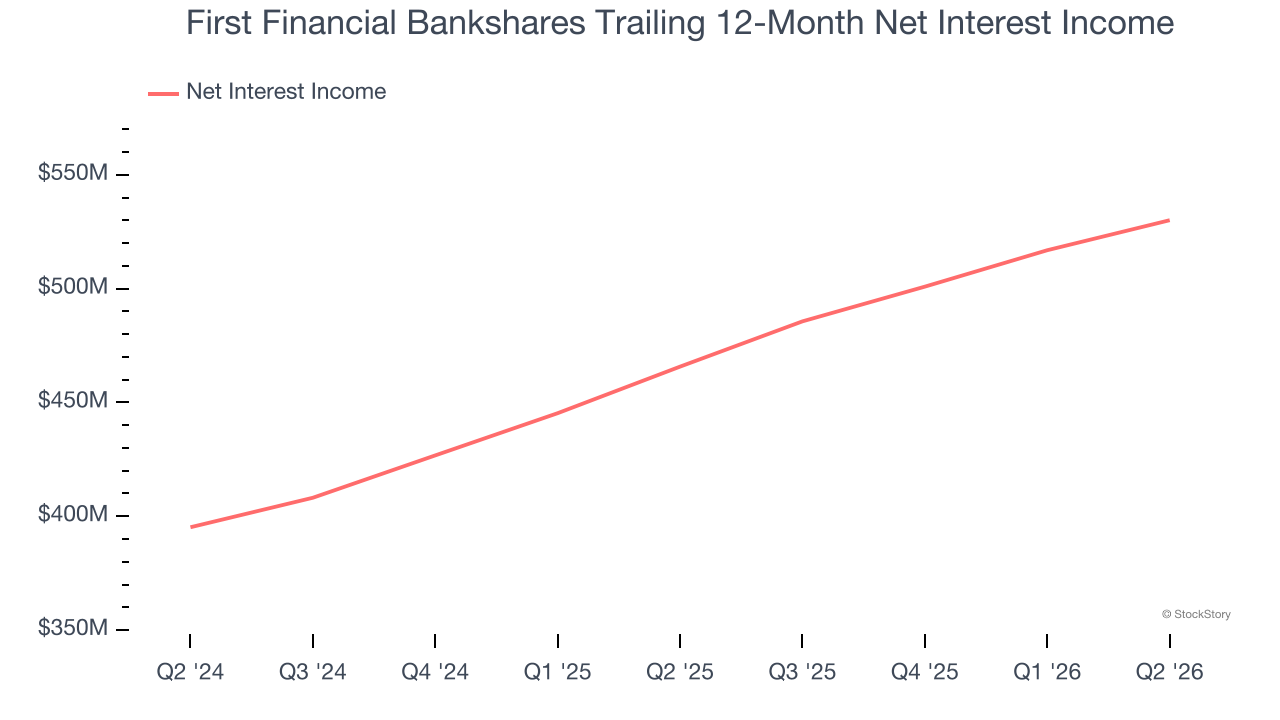
Our experience and research show the market cares primarily about a bank’s net interest income growth as one-time fees are considered a lower-quality and non-recurring revenue source.
First Financial Bankshares’s net interest income has grown at a 8.1% annualized rate over the last five years, worse than the broader banking industry.
3. EPS Barely Growing
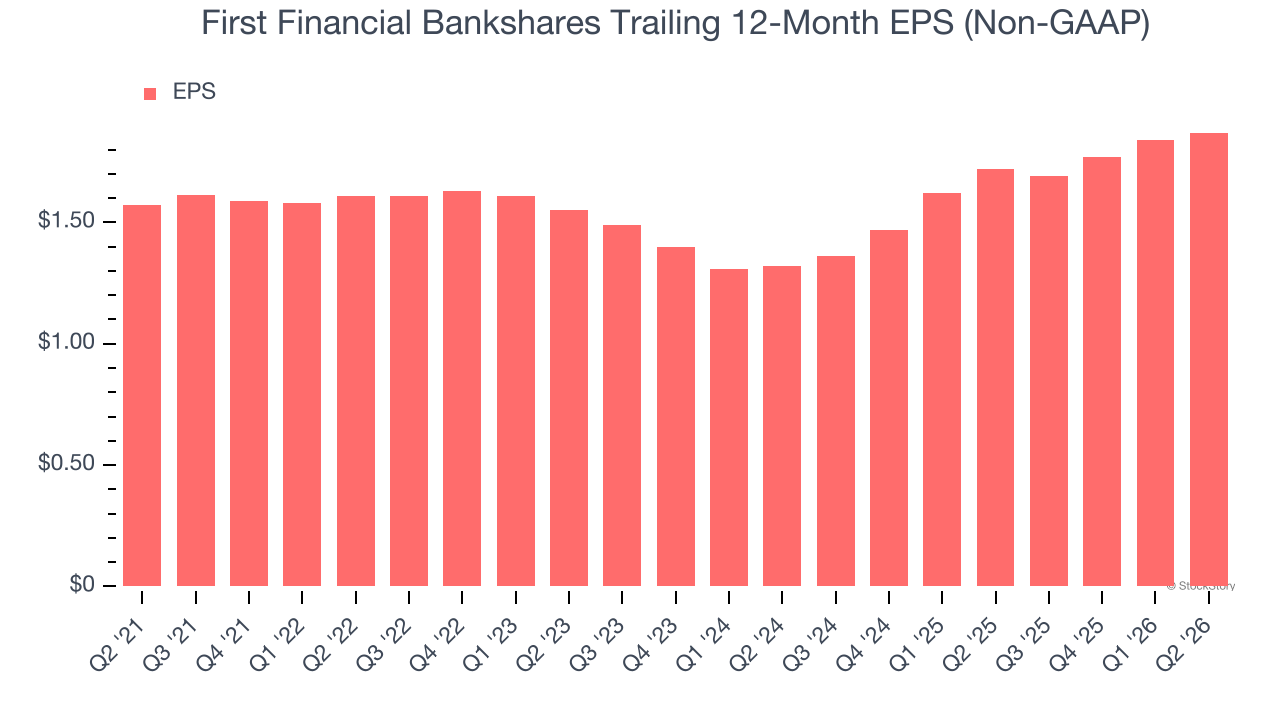
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
First Financial Bankshares’s EPS grew at a weak 3.5% compounded annual growth rate over the last five years, lower than its 5.7% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
First Financial Bankshares isn’t a terrible business, but it doesn’t pass our quality test. With its shares trailing the market in recent months, the stock trades at 2.2× forward P/B (or $31.93 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - you can find more timely opportunities elsewhere. Let us point you toward the Amazon and PayPal of Latin America.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.