
Expeditors’s 32.6% return over the past six months has outpaced the S&P 500 by 14.2%, and its stock price has climbed to $188.25 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Expeditors, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Expeditors Not Exciting?
We’re glad investors have benefited from the price increase, but we’re passing on Expeditors for now. Here are three reasons why there are better opportunities than EXPD, plus one stock we’d rather own.
1. Long-Term Revenue Growth Flatter Than a Pancake
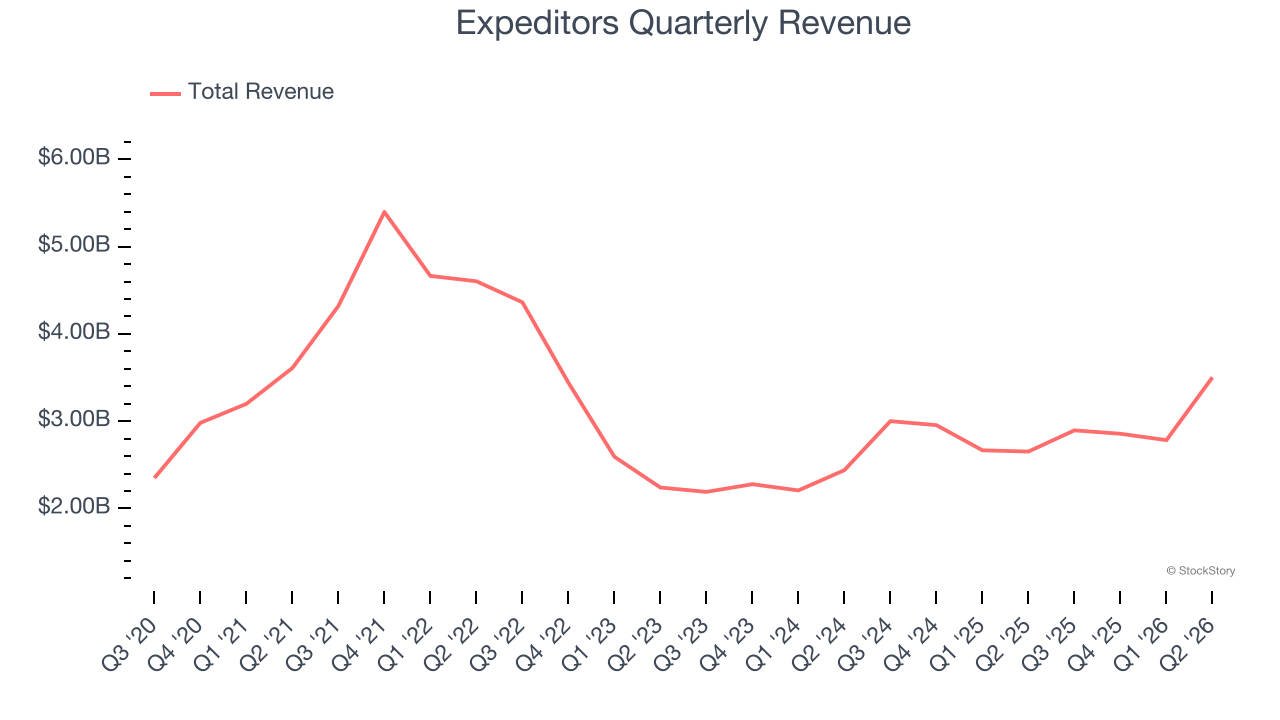
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, Expeditors struggled to consistently increase demand as its $12.04 billion of sales for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of lacking business quality.
2. Low Gross Margin Reveals Weak Structural Profitability
For industrial businesses, cost of sales is usually comprised of the direct labor, raw materials, and supplies needed to offer a product or service. These costs can be impacted by inflation and supply chain dynamics in the short term and a company’s purchasing power and scale over the long term.
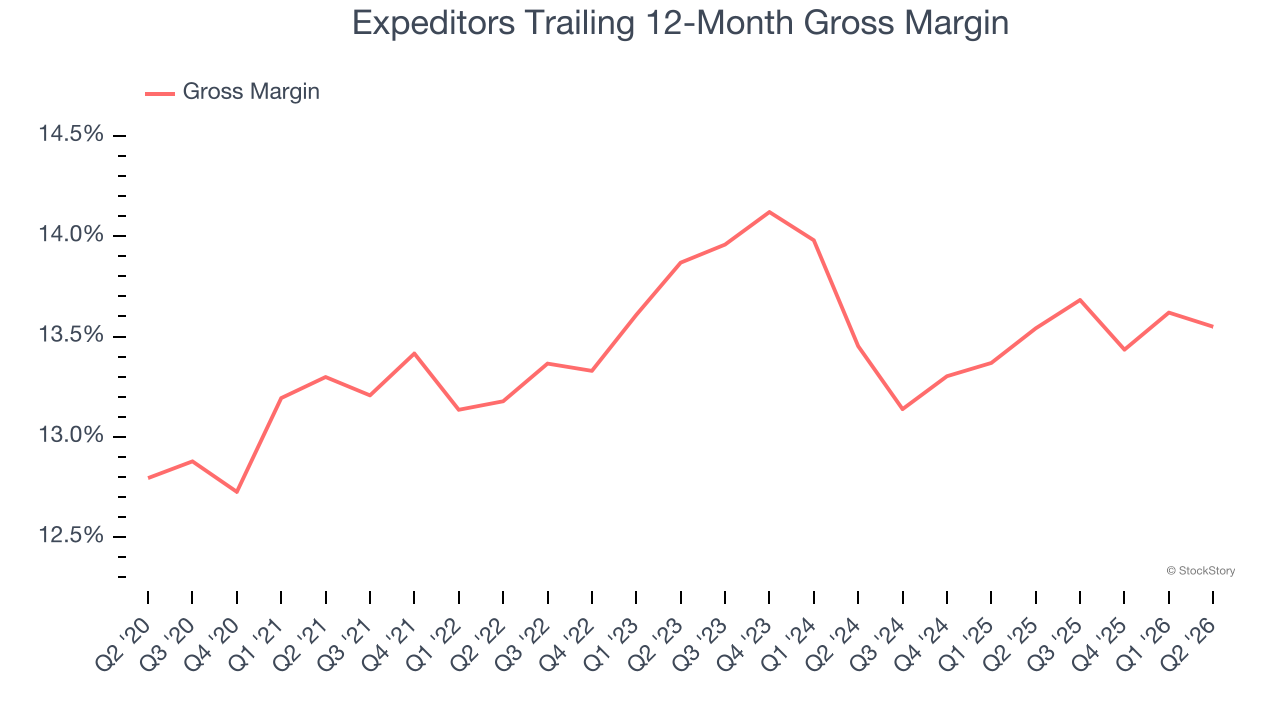
Expeditors has bad unit economics for an industrials business, signaling it operates in a competitive market. As you can see below, it averaged a 13.5% gross margin over the last five years. Said differently, Expeditors had to pay a chunky $86.51 to its suppliers for every $100 in revenue.
3. New Investments Fail to Bear Fruit as ROIC Declines
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
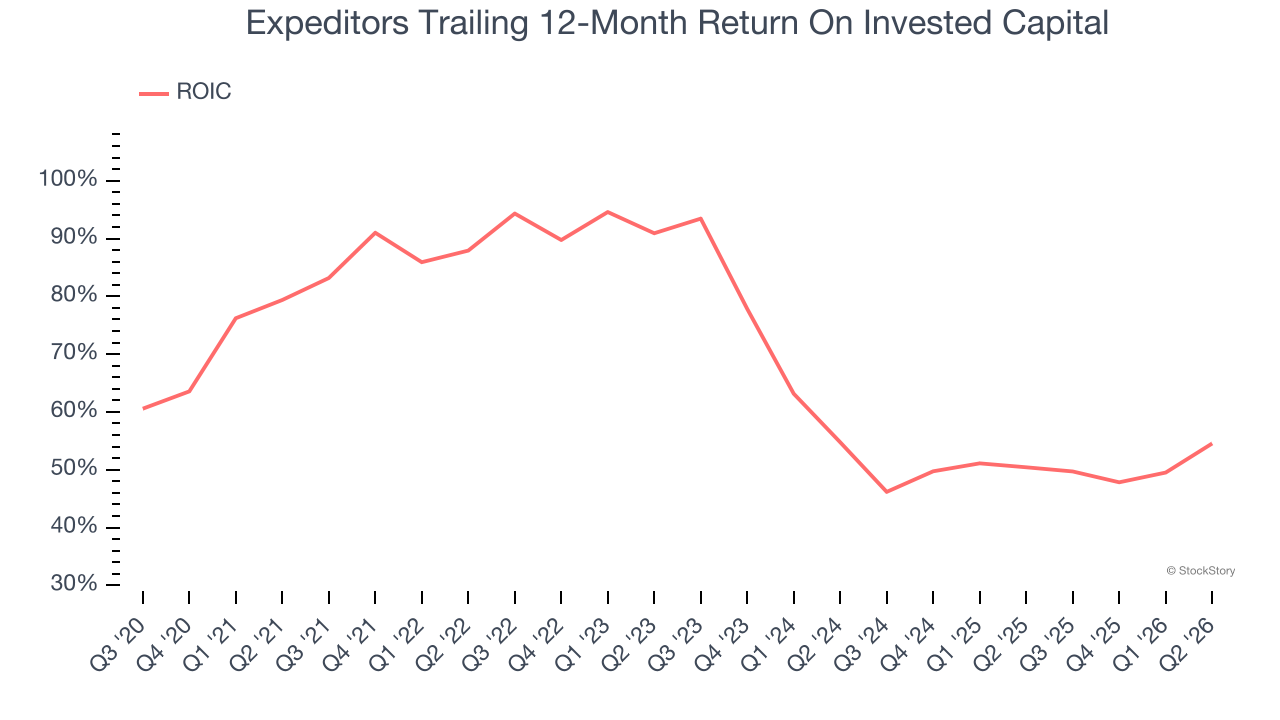
Unfortunately, Expeditors’s ROIC has decreased significantly over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Expeditors’s business quality ultimately falls short of our standards. With its shares beating the market recently, the stock trades at 24.4× forward P/E (or $188.25 per share). Beauty is in the eye of the beholder, but our analysis shows the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. Let us point you toward the most dominant software business in the world.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.