
Over the past six months, Amphastar Pharmaceuticals has been a great trade, beating the S&P 500 by 11.4%. Its stock price has climbed to $24.97, representing a healthy 29.8% increase. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Amphastar Pharmaceuticals, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Amphastar Pharmaceuticals Not Exciting?
We’re happy investors have made money, but we’re sitting this one out for now. Here are three reasons why there are better opportunities than AMPH, plus one stock we’d rather own.
1. Lackluster Revenue Growth
We at StockStory place the most emphasis on long-term growth, but within healthcare, a stretched historical view may miss recent innovations or disruptive industry trends. Amphastar Pharmaceuticals’s recent performance shows its demand has slowed as its annualized revenue growth of 1.2% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 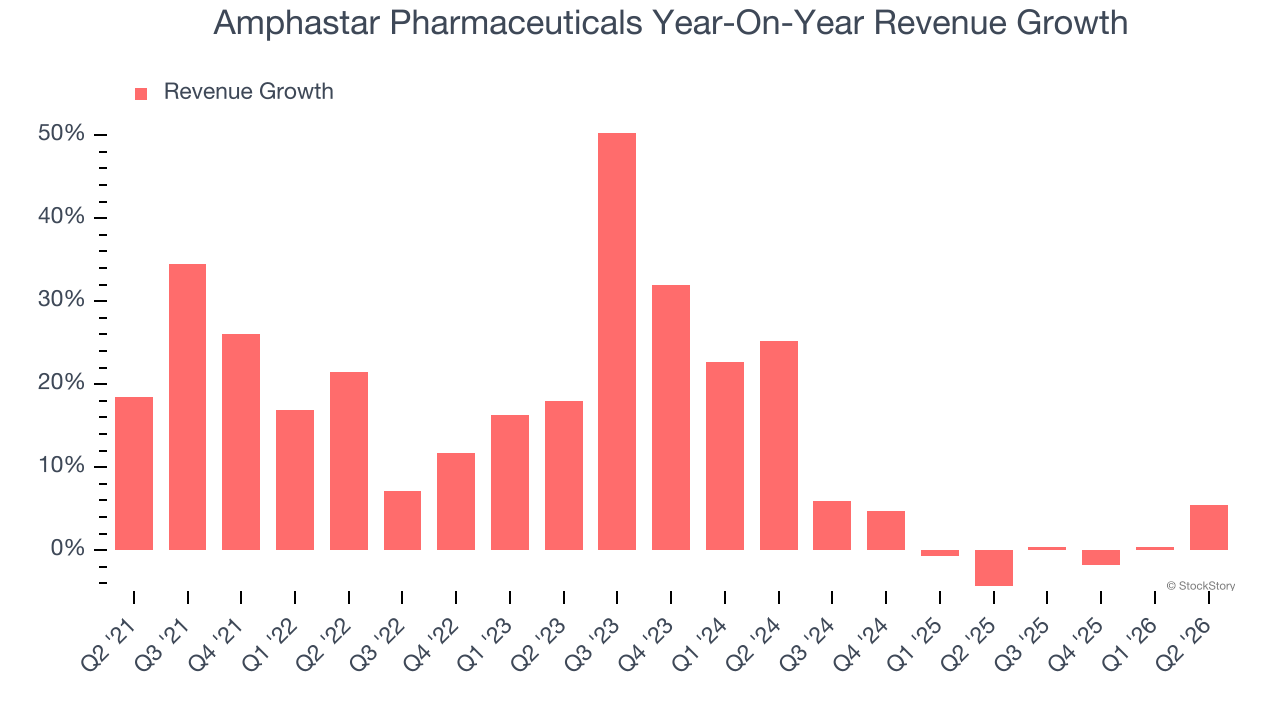
2. Fewer Distribution Channels Limit Its Ceiling
Larger companies benefit from economies of scale, where fixed costs like infrastructure, technology, and administration are spread over a higher volume of goods or services, reducing the cost per unit. Scale can also lead to bargaining power with suppliers, greater brand recognition, and more investment firepower. A virtuous cycle can ensue if a scaled company plays its cards right.
With just $730 million in revenue over the past 12 months, Amphastar Pharmaceuticals is a small company in an industry where scale matters. This makes it difficult to build trust with customers because healthcare is heavily regulated, complex, and resource-intensive.
3. Shrinking Adjusted Operating Margin
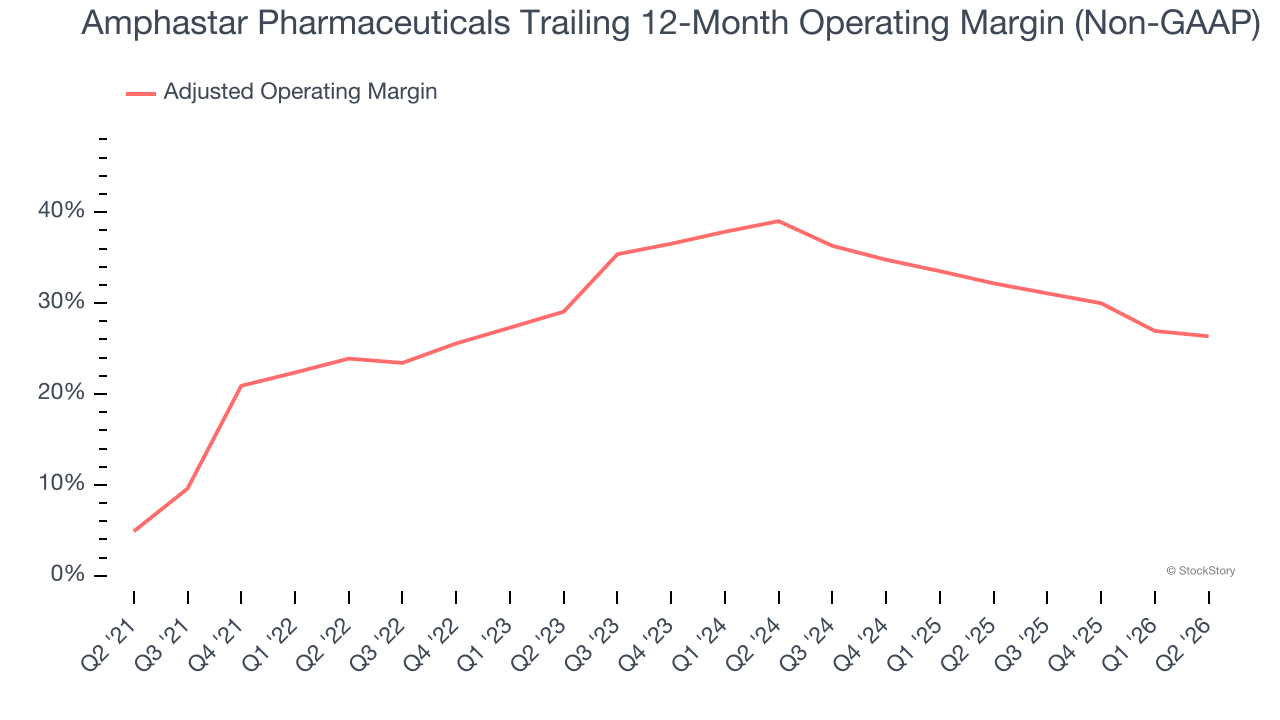
Adjusted operating margin is one of the best measures of profitability because it tells us how much money a company takes home after subtracting all core expenses, like marketing and R&D. It also removes various one-time costs to paint a better picture of normalized profits.
Looking at the trend in its profitability, Amphastar Pharmaceuticals’s adjusted operating margin decreased by 12.7 percentage points over the last two years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its adjusted operating margin for the trailing 12 months was 26.4%.
Final Judgment
Amphastar Pharmaceuticals isn’t a terrible business, but it isn’t one of our picks. With its shares beating the market recently, the stock trades at 7.6× forward P/E (or $24.97 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.