
Over the past six months, Myriad Genetics’s stock price fell to $4.01. Shareholders have lost 13% of their capital, which is disappointing considering the S&P 500 has climbed by 18.4%. This was partly due to its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy Myriad Genetics, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Myriad Genetics Will Underperform?
Even though the stock has become cheaper, we don’t have much confidence in Myriad Genetics. Here are three reasons you should be careful with MYGN, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
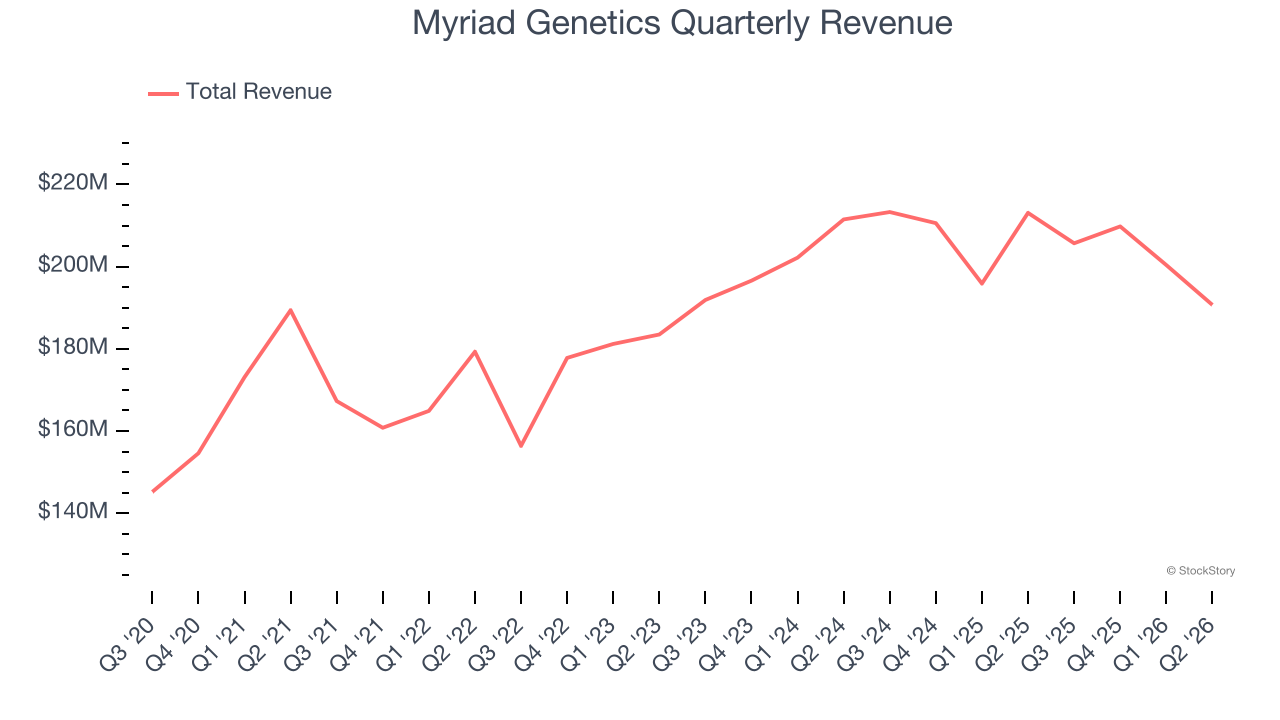
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Myriad Genetics grew its sales at a mediocre 4% compounded annual growth rate. This was below our standard for the healthcare sector.
2. EPS Trending Down
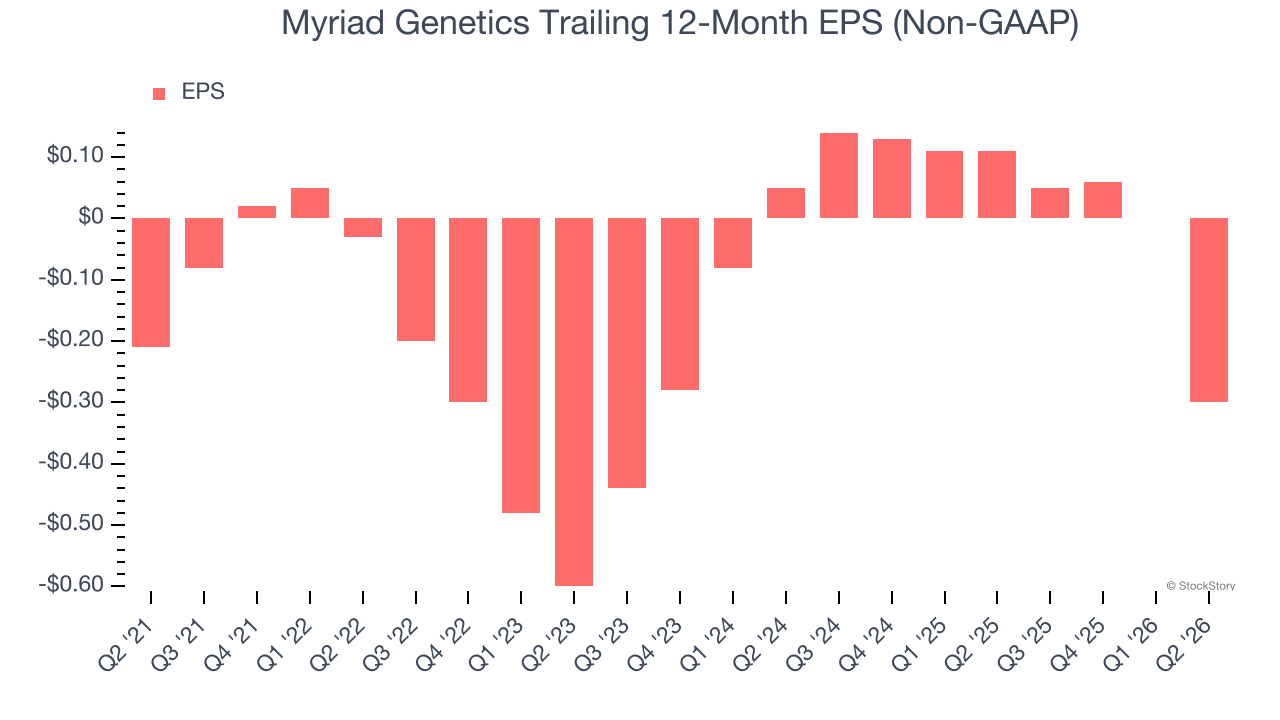
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Myriad Genetics’s earnings losses deepened over the last five years as its EPS dropped 7.4% annually. We tend to steer our readers away from companies with falling EPS, where diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, Myriad Genetics’s low margin of safety could leave its stock price susceptible to large downswings.
3. Restricted Access to Capital Increases Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Myriad Genetics posted negative $3.9 million of EBITDA over the last 12 months, and its $210.5 million of debt exceeds the $115.2 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
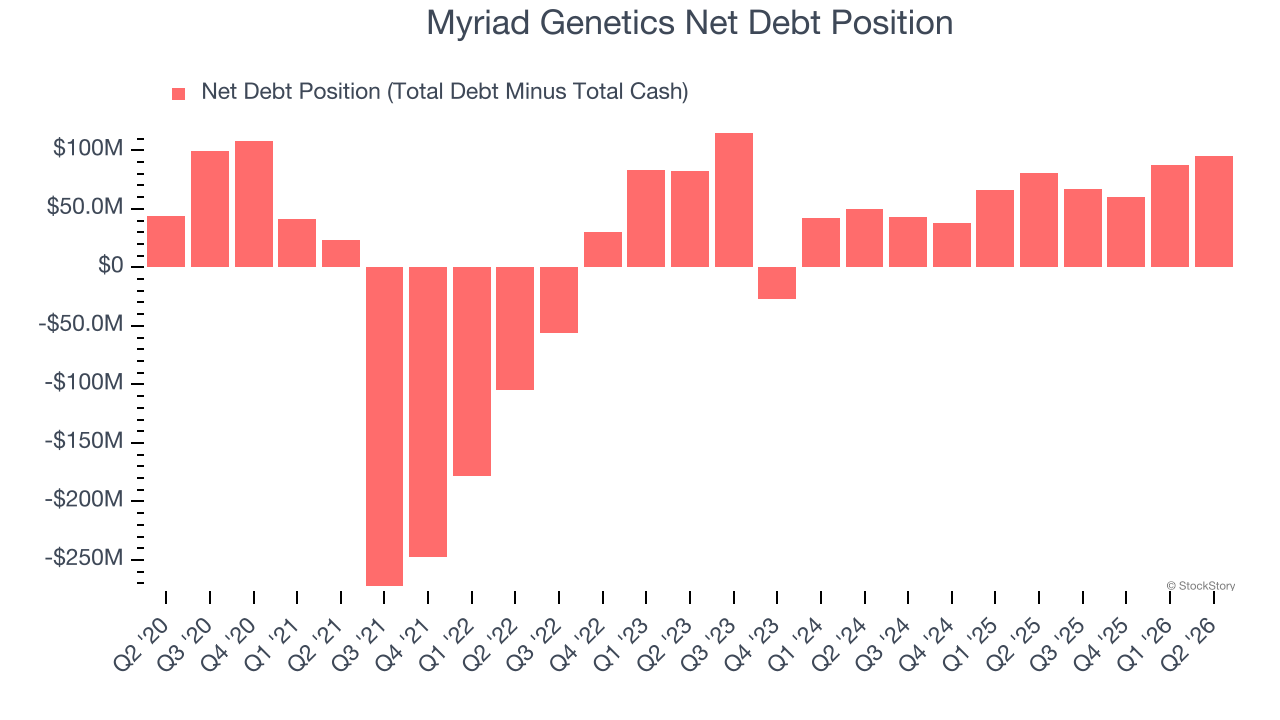
We implore our readers to tread carefully because credit agencies could downgrade Myriad Genetics if its unprofitable ways continue, making incremental borrowing more expensive and restricting growth prospects. The company could also be backed into a corner if the market turns unexpectedly. We hope Myriad Genetics can improve its profitability and remain cautious until then.
Final Judgment
We see the value of companies making people healthier, but in the case of Myriad Genetics, we’re out. Following the recent decline, the stock trades at $4.01 per share (or a forward price-to-sales ratio of 0.5×). The market typically values companies like Myriad Genetics based on their anticipated profits for the next 12 months, but it expects the business to lose money. We also think the upside isn’t great compared to the potential downside here - there are more exciting stocks to buy. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Like More Than Myriad Genetics
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.