
FB Financial has been treading water for the past six months, recording a small return of 1.1% while holding steady at $52.79. The stock also fell short of the S&P 500’s 18.4% gain during that period.
Is now the time to buy FB Financial, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is FB Financial Not Exciting?
We’re cautious about FB Financial. Here are three reasons why FBK doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income.
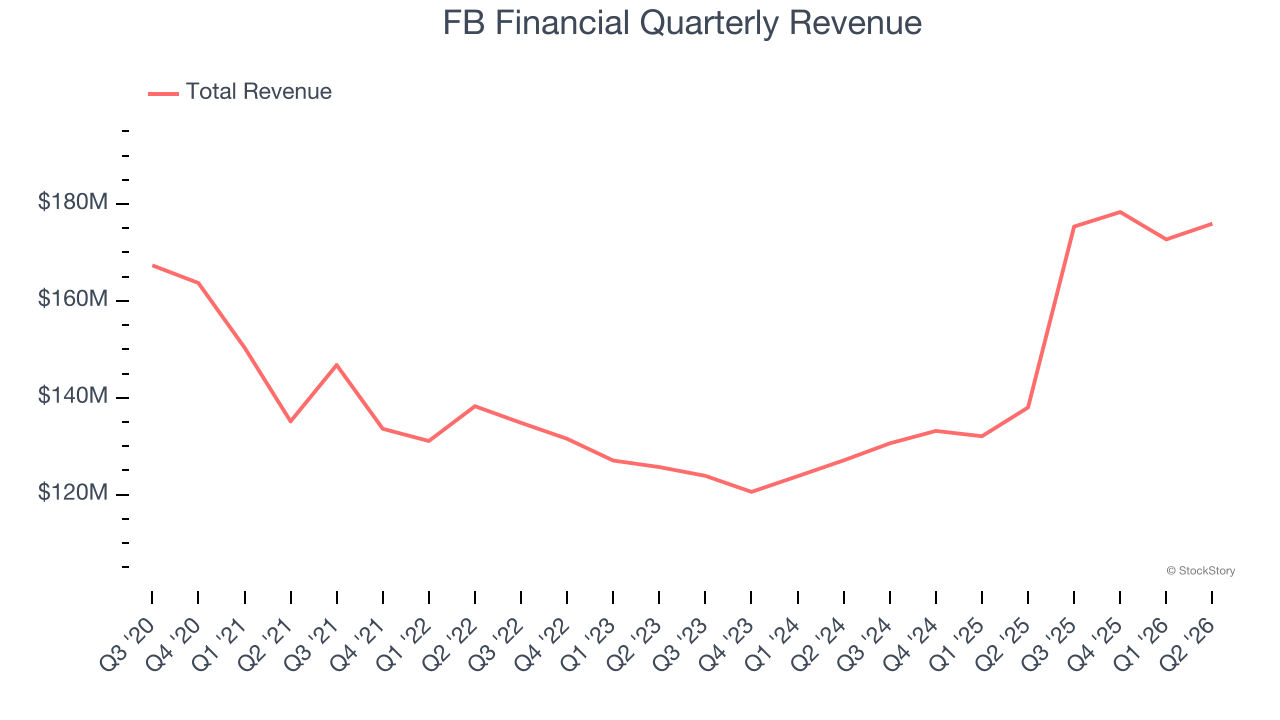
Over the last five years, FB Financial grew its revenue at a sluggish 2.6% compounded annual growth rate. This was below our standards.
2. Projected Net Interest Income Growth Is Slim
Forecasted net interest income by Wall Street analysts signals a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect FB Financial’s net interest income to rise by 5.2%, a deceleration versus its 21% annualized growth for the past two years. This projection is below its 21% annualized growth rate for the past two years.
3. EPS Growth Has Stalled
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
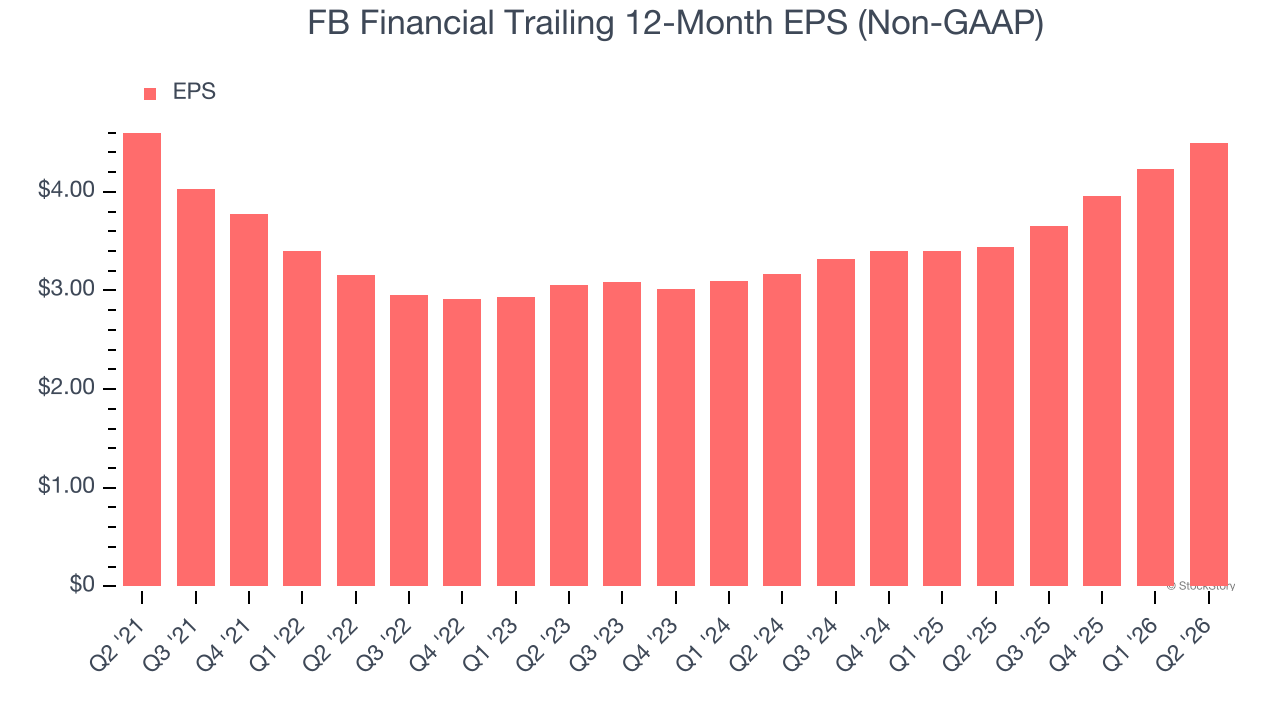
FB Financial’s flat EPS over the last five years was below its 2.6% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
FB Financial isn’t a terrible business, but it isn’t one of our picks. With its shares lagging the market recently, the stock trades at 1.3× forward P/B (or $52.79 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. Let us point you toward a safe-and-steady industrials business benefiting from an upgrade cycle.
Stocks We Would Buy Instead of FB Financial
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.