
Match Group has had an impressive run over the past six months as its shares have beaten the S&P 500 by 16%. The stock now trades at $40.84, marking a 34.4% gain. This performance may have investors wondering how to approach the situation.
Is it too late to buy MTCH? Find out in our full research report, it’s free.
Why Does MTCH Stock Spark Debate?
Originally started as a dial-up service before widespread internet adoption, Match (NASDAQ:MTCH) was an early innovator in online dating and today has a portfolio of apps including Tinder, Hinge, Archer, and OkCupid.
Two Things to Like:
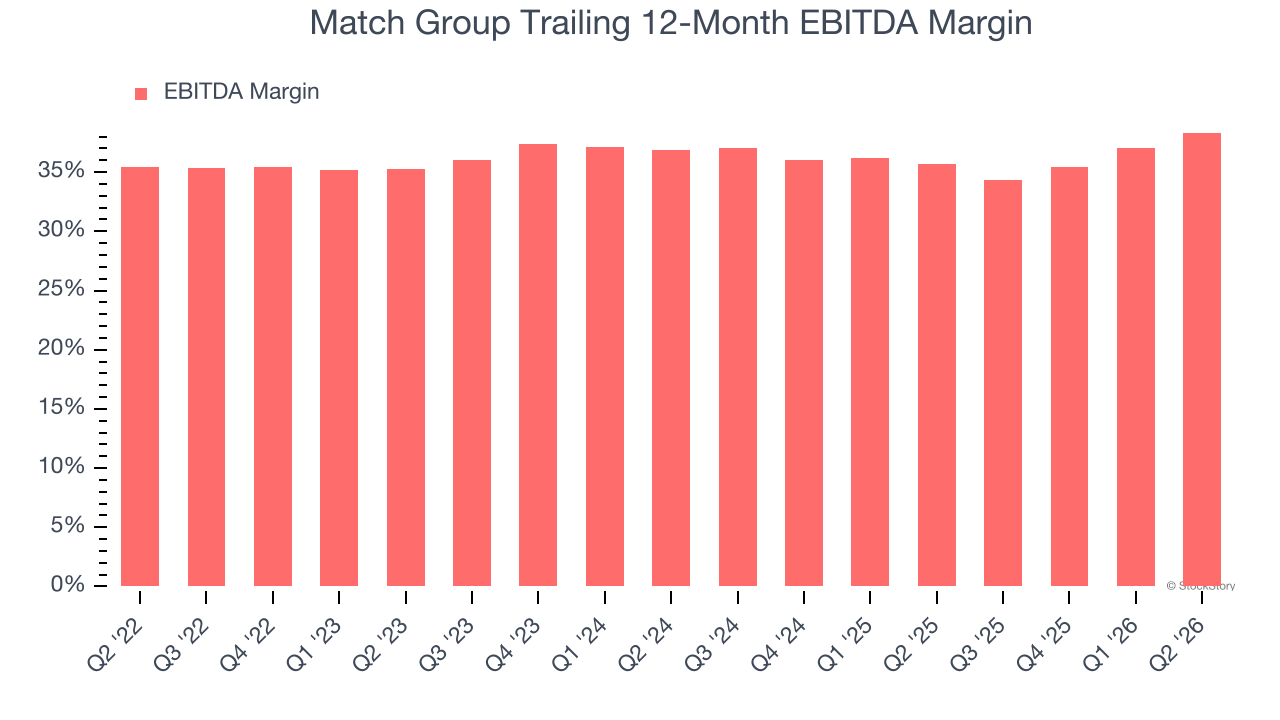
1. EBITDA Margin Reveals a Well-Run Organization
EBITDA is a good way of judging operating profitability for consumer internet companies because it excludes various one-time or non-cash expenses (depreciation), providing a more standardized view of the business’s profit potential.
Match Group has been a well-oiled machine over the last two years. It demonstrated elite profitability for a consumer internet business, boasting an average EBITDA margin of 37%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
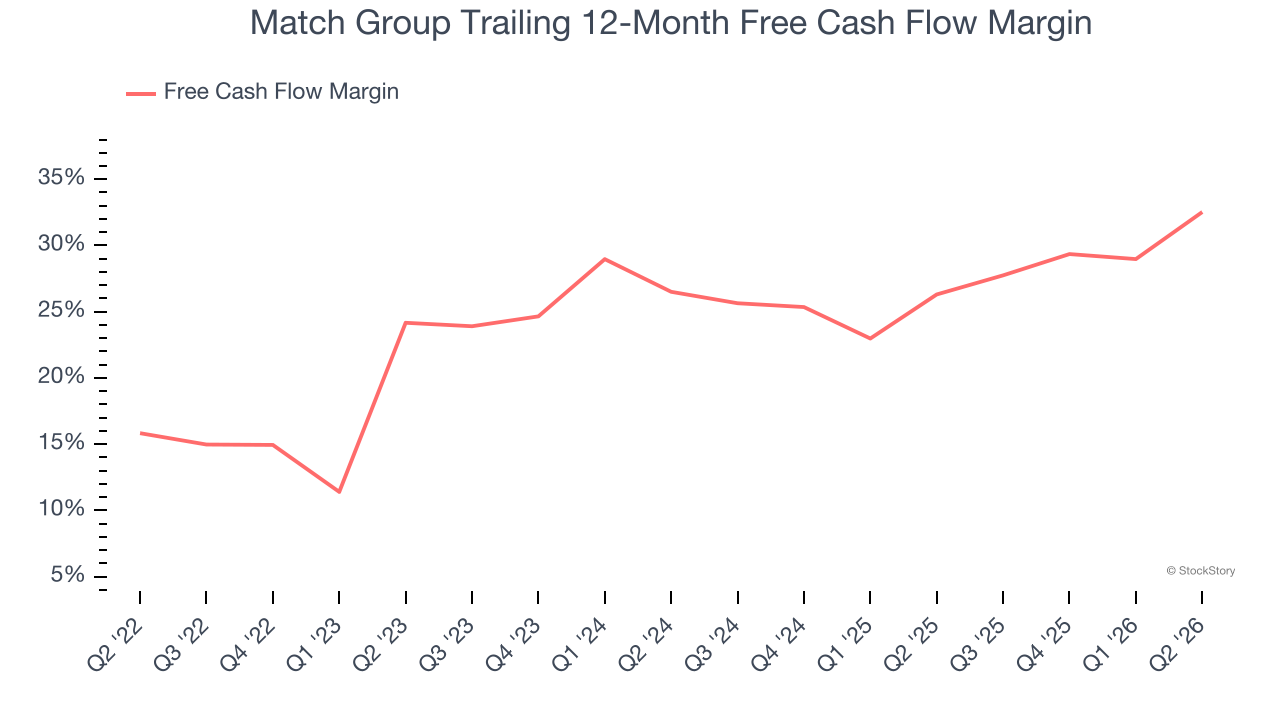
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Match Group has shown terrific cash profitability, driven by its lucrative business model and cost-effective customer acquisition strategy that enable it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging 29.4% over the last two years.
One Reason to Be Careful:
Declining Payers Reflect Product Weakness
As a subscription-based app, Match Group generates revenue growth by expanding both its subscriber base and the amount each subscriber spends over time.
Match Group struggled with new customer acquisition over the last two years as its payers have declined by 4.6% annually to 13.3 million in the latest quarter. This performance isn’t ideal because internet usage is secular, meaning there are typically unaddressed market opportunities. If Match Group wants to accelerate growth, it likely needs to enhance the appeal of its current offerings or innovate with new products. 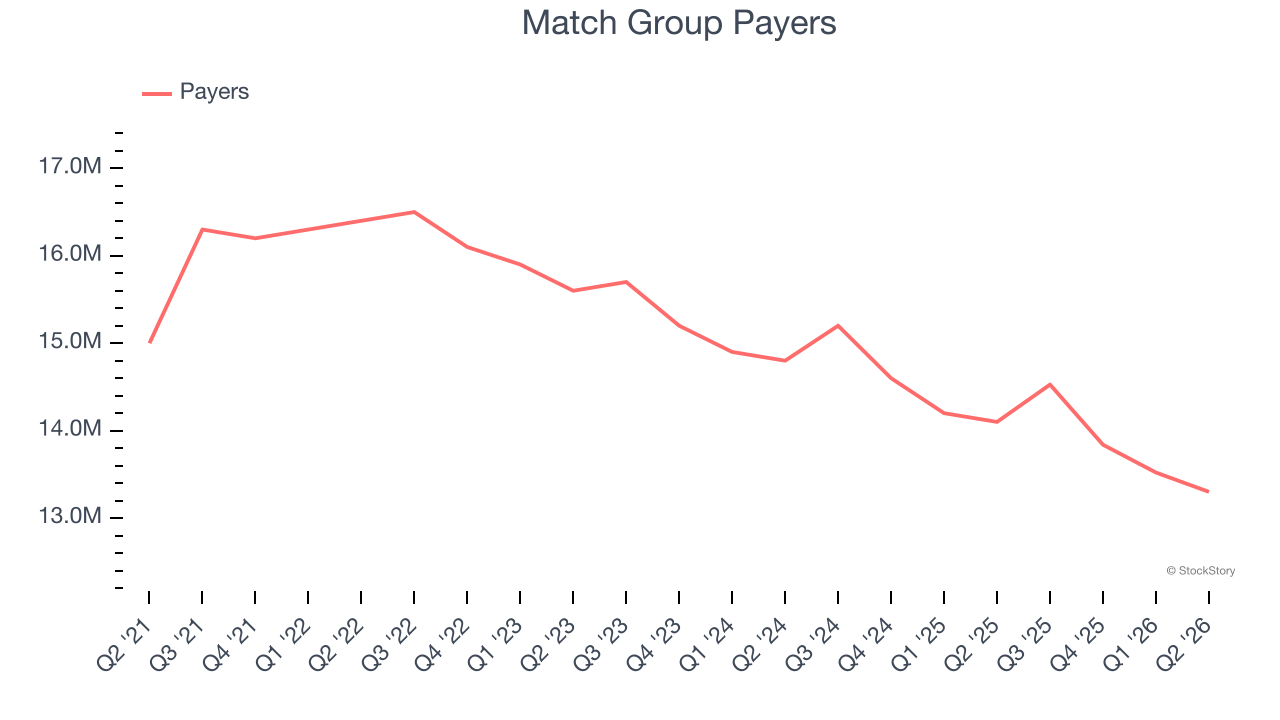
Final Judgment
Match Group’s positive characteristics outweigh the negatives, and with its shares topping the market in recent months, the stock trades at 9.4× forward EV/EBITDA (or $40.84 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.