

Cactus has had an impressive run over the past six months as its shares have beaten the S&P 500 by 18.3%. The stock now trades at $66.05, marking a 36.7% gain. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Following the strength, is WHD a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why Does WHD Stock Spark Debate?
Named for the spiky wellhead equipment that reminded founders of desert cacti, Cactus (NYSE:WHD) manufactures wellheads, valves, and spoolable pipes used in drilling and producing oil and gas wells.
Two Positive Attributes:
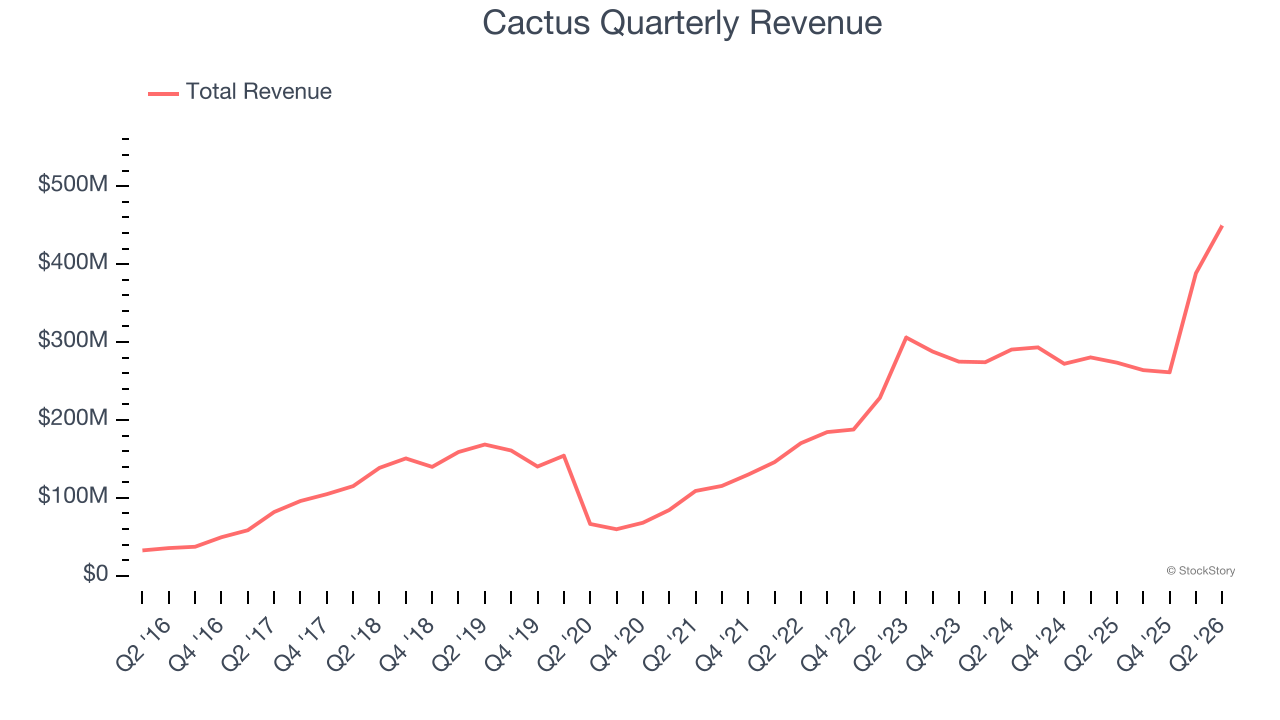
1. Skyrocketing Revenue Shows Strong Momentum
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Over the last five years, Cactus grew its sales at an incredible 33.5% compounded annual growth rate. Its growth surpassed the average energy upstream and integrated energy company and shows its offerings resonate with customers.
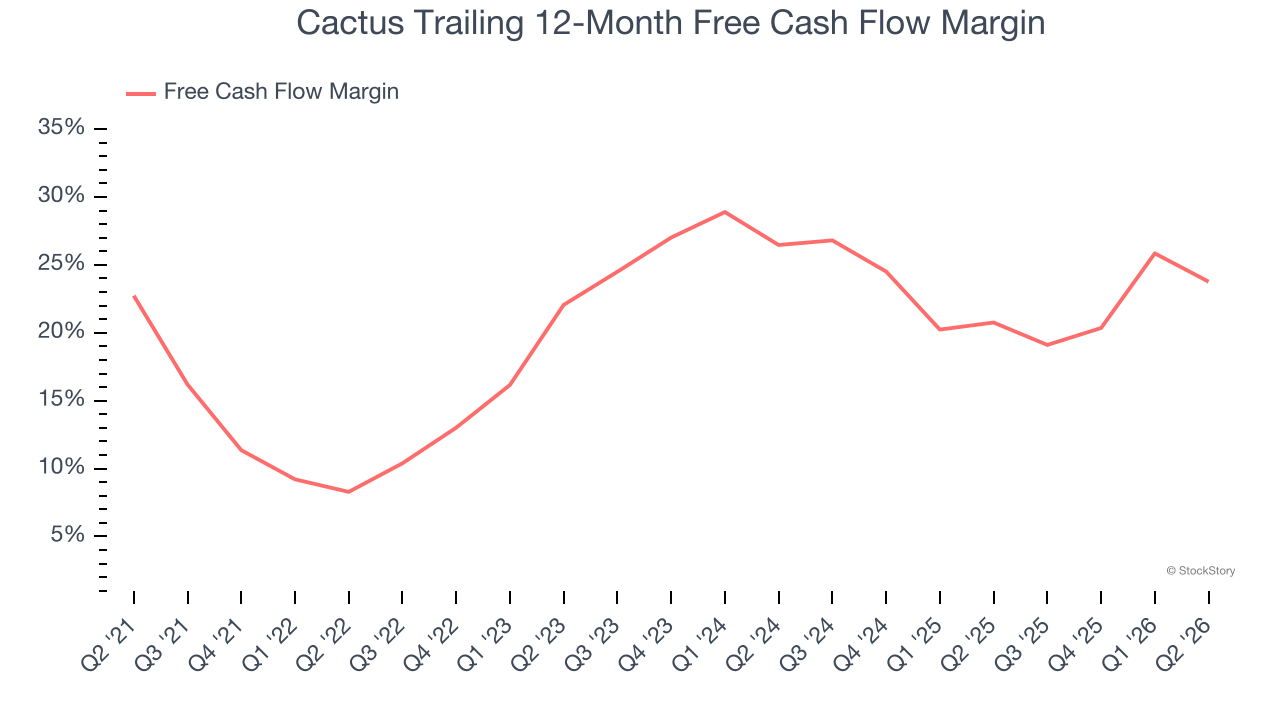
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Cactus has shown terrific cash profitability, enabling it to reinvest, return capital to investors, and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 21.7% over the last five years.
One Reason to Be Careful:
Fewer Distribution Channels Limit Its Ceiling
The scale of a company’s revenue base is an important lens through which to view the topline, as it signals whether a producer has gone from a vulnerable commodity taker into a durable operating platform. Larger producers generate revenue across many wells, pads, takeaway routes, and geographies rather than relying on a single field or drilling program.
Cactus’s $1.36 billion of revenue in the last year is pretty small for the industry, suggesting the company hasn’t hit a level of diversification where investors can sleep easy at night.
Final Judgment
Cactus has huge potential even though it has some open questions, and with its shares beating the market recently, the stock trades at 21× forward P/E (or $66.05 per share). Is now the time to initiate a position? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.