

While the S&P 500 is up 18.4% since March 2026, Standex (currently trading at $275.55 per share) has lagged behind, posting a return of 6%. This may have investors wondering how to approach the situation.
Does this present a buying opportunity for SXI? Or does the price properly account for its business quality and fundamentals?
Why Does Standex Spark Debate?
Holding over 500 patents globally, Standex (NYSE:SXI) is a manufacturer and distributor of industrial components for various sectors.
Two Things to Like:
1. Skyrocketing Revenue Shows Strong Momentum
Long-term growth is the most important, but within industrials, a stretched historical view may miss new industry trends or demand cycles. Standex’s annualized revenue growth of 11.2% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 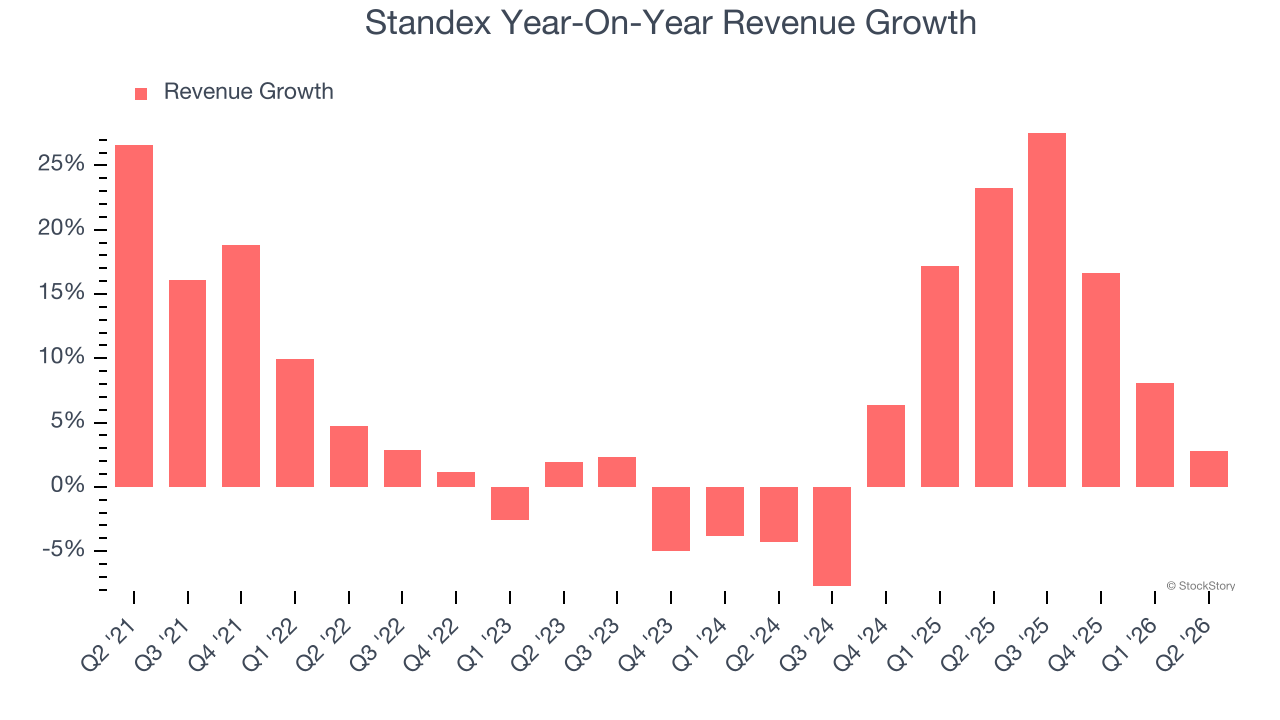
2. Operating Margin Reveals a Well-Run Organization
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
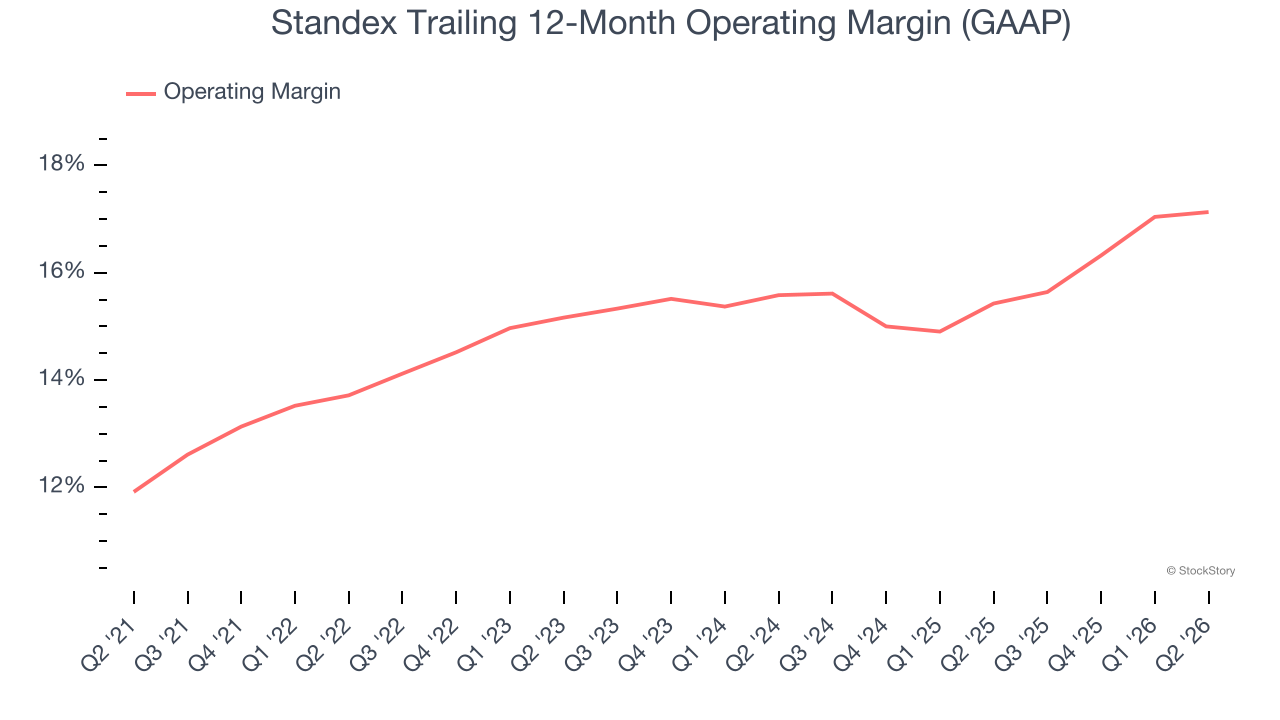
Standex has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, boasting an average operating margin of 15.5%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
One Reason to Be Careful:
New Investments Fail to Bear Fruit as ROIC Declines
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
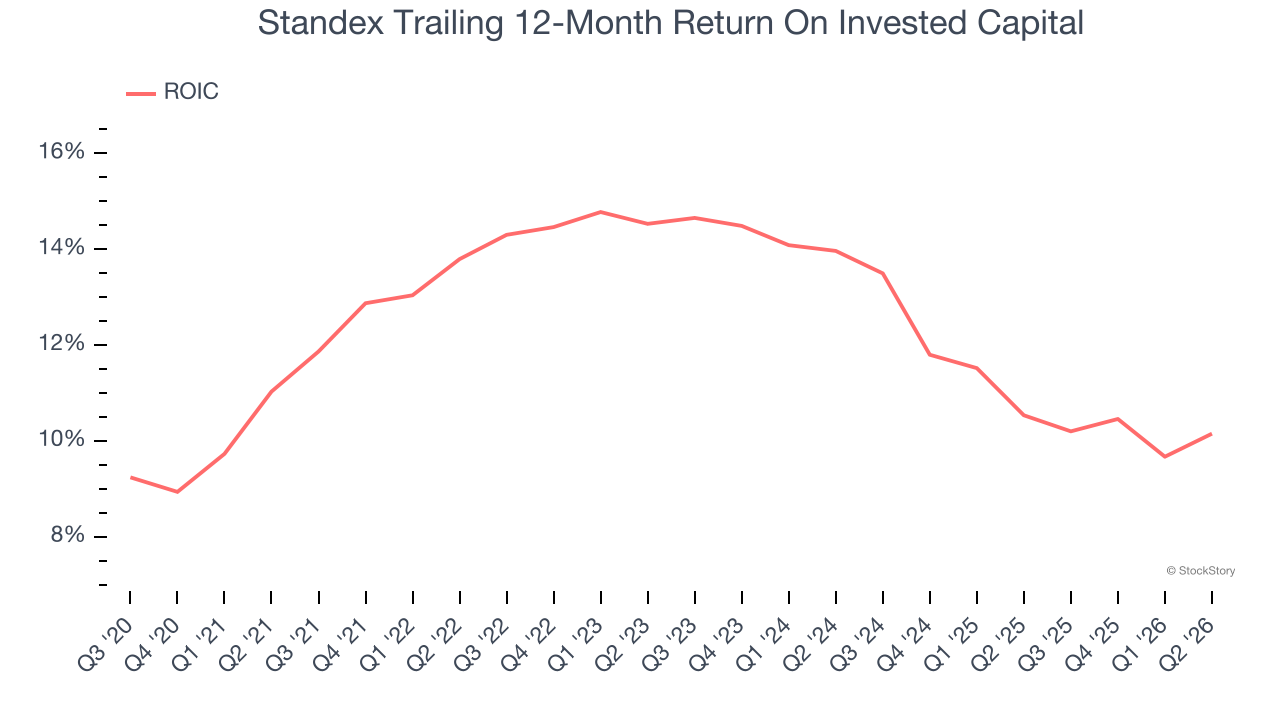
Over the last few years, Standex’s ROIC averaged 3.8 percentage point decreases each year. Only time will tell if its new bets can bear fruit and potentially reverse the trend.
Final Judgment
Standex’s merits more than compensate for its flaws. With its shares lagging the market recently, the stock trades at 27.2× forward P/E (or $275.55 per share). Is now a good time to initiate a position? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Standex
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.