

Wrapping up Q2 earnings, we look at the numbers and key takeaways for the vertical software stocks, including Guidewire Software (NYSE:GWRE) and its peers.
Software is eating the world, and while a large number of solutions such as project management or video conferencing software can be useful to a wide array of industries, some have very specific needs. As a result, vertical software, which addresses industry-specific workflows, is growing and fueled by the pressures to improve productivity, whether it be for a life sciences, education, or banking company.
The 4 vertical software stocks we track reported a strong Q2. As a group, revenues beat analysts’ consensus estimates by 2.6% while next quarter’s revenue guidance was 3.3% below.
While some vertical software stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 4.7% since the latest earnings results.
Guidewire Software (NYSE:GWRE)
With its systems powering the operations of hundreds of insurance brands across 42 countries, Guidewire Software (NYSE:GWRE) provides a technology platform that helps property and casualty insurance companies manage their core operations, digital engagement, and analytics.
Guidewire Software reported revenues of $411.1 million, up 15.3% year on year. This print exceeded analysts’ expectations by 2.2%. Overall, it was a strong quarter for the company with an impressive beat of analysts’ billings estimates and a solid beat of analysts’ adjusted operating income estimates.
“We closed a great fourth quarter, capping off an incredible year of expanding demand,” said Mike Rosenbaum, chief executive officer, Guidewire. “Customers are deepening their commitments to Guidewire’s core offerings and expanding with new pricing and AI focused products. AI is driving our momentum, as more of our insurance customers choose to align their AI transformation with Guidewire.”
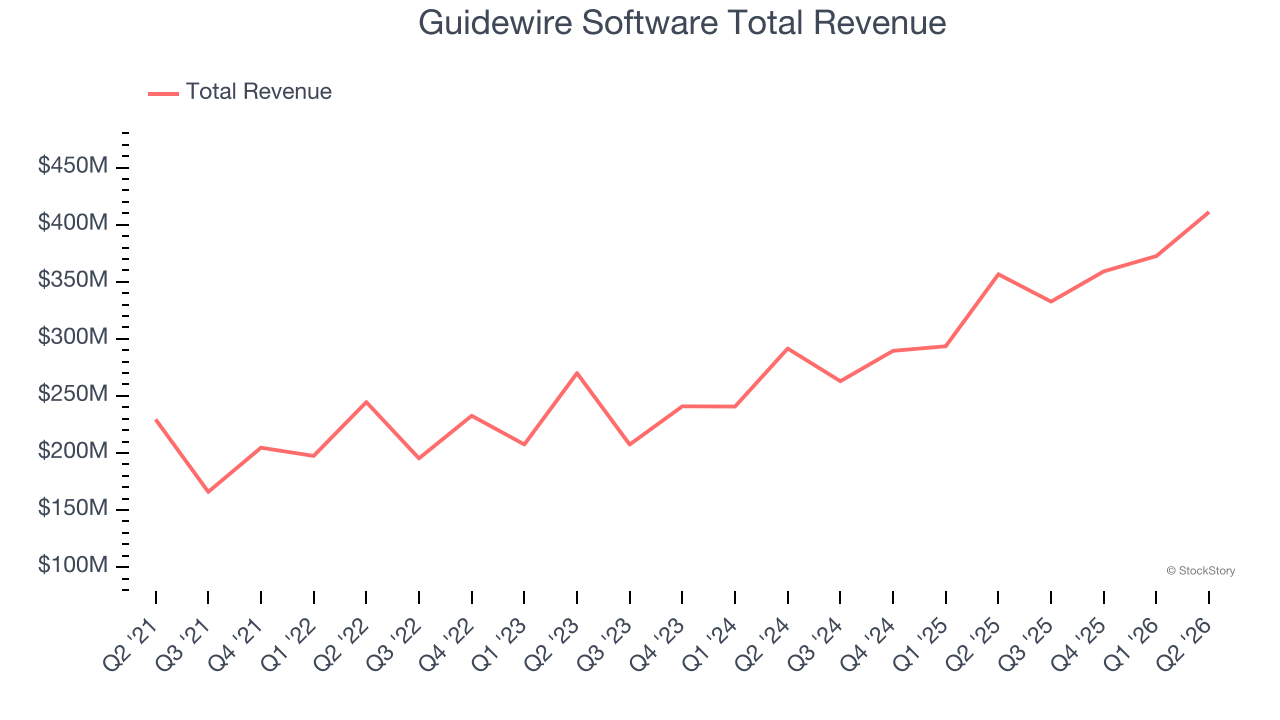
Guidewire Software scored the fastest revenue growth of the whole group. Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 25.8% since reporting and currently trades at $150.54.
Best Q2: Alarm.com (NASDAQ:ALRM)
Processing over 325 billion data points annually from more than 150 million connected devices, Alarm.com (NASDAQ:ALRM) provides cloud-based platforms that enable residential and commercial property owners to remotely monitor and control their security, video, energy, and other connected devices.
Alarm.com reported revenues of $277.7 million, up 9.2% year on year, outperforming analysts’ expectations by 4.9%. The business had an exceptional quarter with an impressive beat of analysts’ billings estimates and full-year EBITDA guidance exceeding analysts’ expectations.
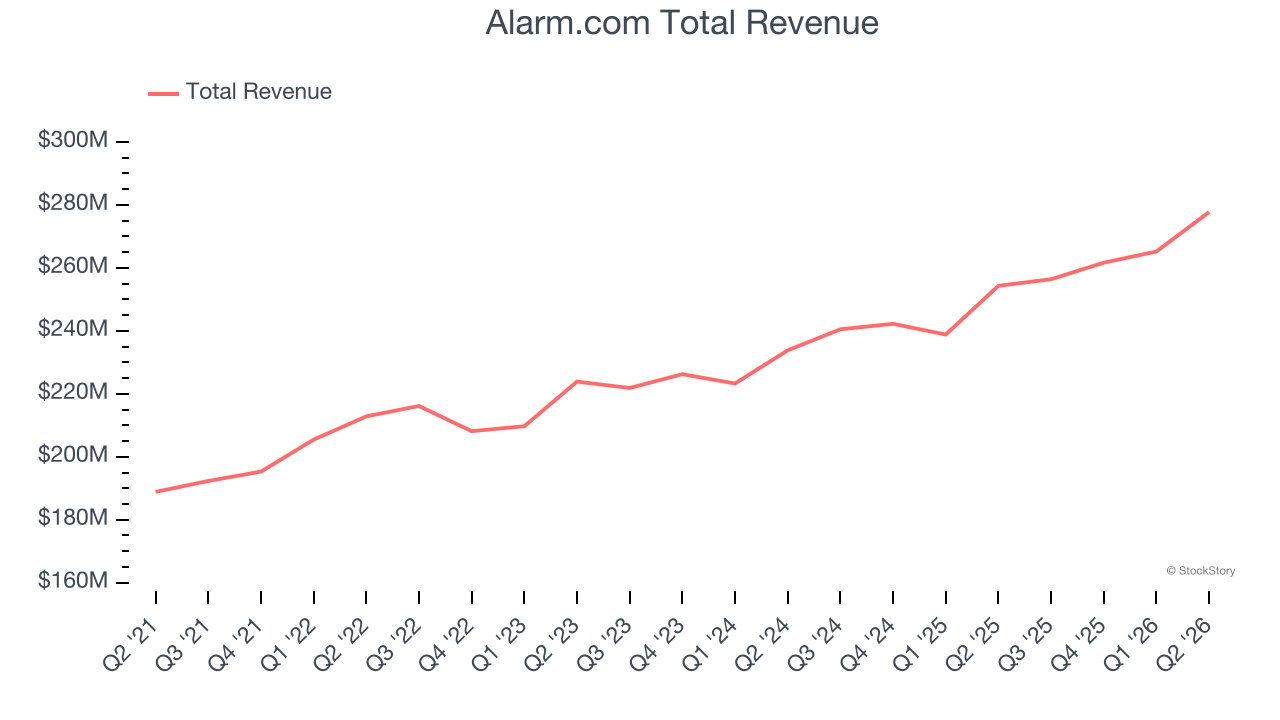
Alarm.com pulled off the biggest analyst estimate beat and highest full-year guidance raise in the group. Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 5.6% since reporting. It currently trades at $53.16.
Is now the time to buy Alarm.com? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Bentley Systems (NASDAQ:BSY)
Pioneering the concept of "digital twins" for infrastructure projects long before it became an industry buzzword, Bentley Systems (NASDAQ:BSY) provides software solutions that help engineers design, build, and operate infrastructure projects across sectors including roads, bridges, utilities, mining, and industrial facilities.
Bentley Systems reported revenues of $410.7 million, up 12.8% year on year, in line with analysts’ expectations. It was a mixed quarter as it posted a decent beat of analysts’ adjusted operating income estimates but a slight miss of analysts’ billings estimates.
Bentley Systems delivered the weakest performance against analyst estimates among its peers. As expected, the stock is down 10.5% since the results and currently trades at $32.24.
Read our full analysis of Bentley Systems’s results here.
Manhattan Associates (NASDAQ:MANH)
Built on a "versionless" cloud architecture that delivers quarterly updates to all customers, Manhattan Associates (NASDAQ:MANH) develops cloud-based software that helps retailers, wholesalers, and manufacturers manage their supply chains, inventory, and omnichannel operations.
Manhattan Associates reported revenues of $297.8 million, up 9.3% year on year. This number beat analysts’ expectations by 3.5%. Overall, it was a very strong quarter as it also recorded full-year EPS guidance beating analysts’ expectations and an impressive beat of analysts’ adjusted operating income estimates.
Manhattan Associates had the weakest full-year guidance update of the whole group. The stock is up 23.3% since reporting and currently trades at $207.29.
Read our full, actionable report on Manhattan Associates here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.