

Over the past six months, Advanced Drainage’s stock price fell to $130.85. Shareholders have lost 5.1% of their capital, which is disappointing considering the S&P 500 has climbed by 18%. This might have investors contemplating their next move.
Is there a buying opportunity in Advanced Drainage, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Advanced Drainage Not Exciting?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons you should be careful with WMS, plus one stock we’d rather own.
1. Lackluster Revenue Growth
We at StockStory place the most emphasis on long-term growth, but within industrials, a stretched historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Advanced Drainage’s recent performance shows its demand has slowed as its annualized revenue growth of 5.2% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 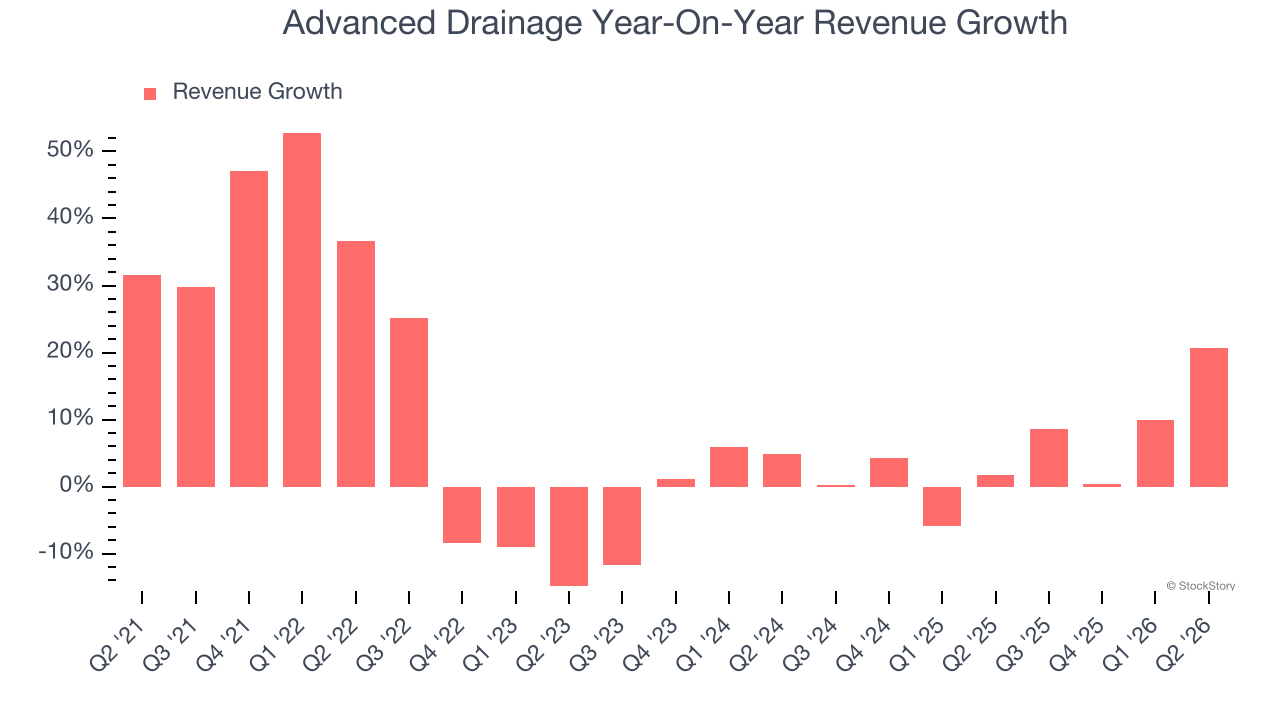
2. Recent EPS Growth Below Our Standards
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
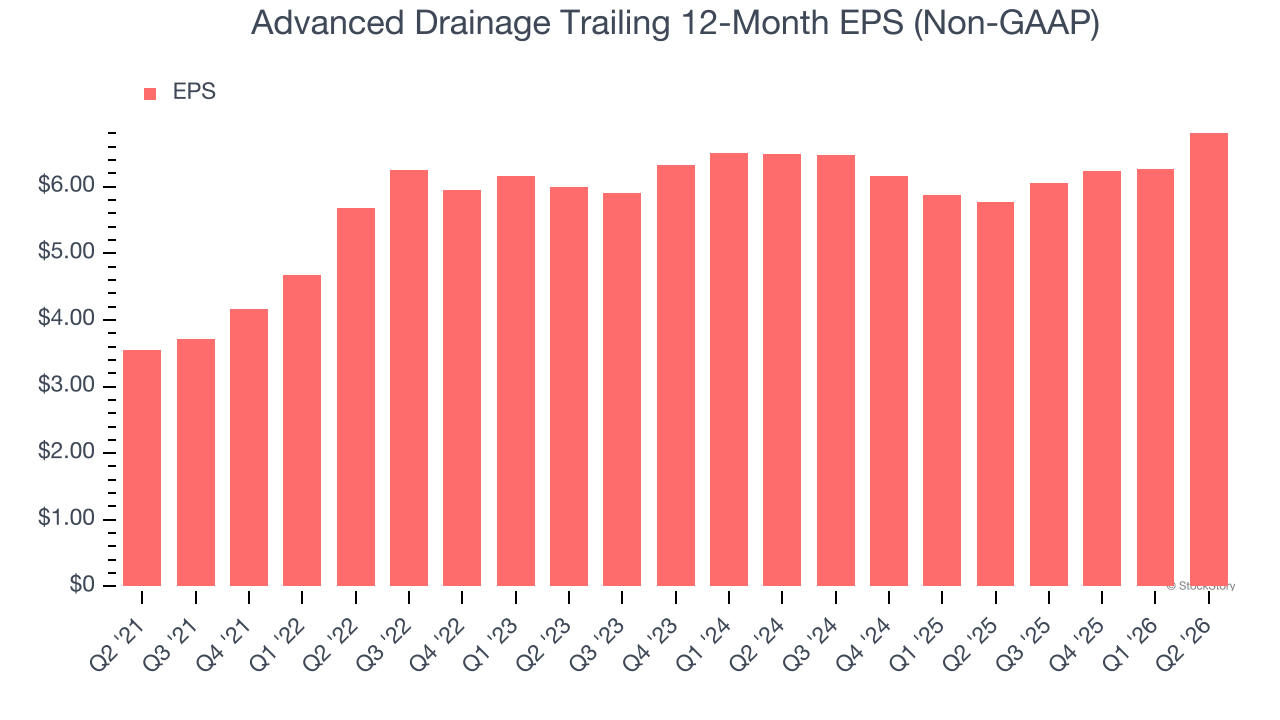
Advanced Drainage’s EPS grew at a weak 2.4% compounded annual growth rate over the last two years, lower than its 5.2% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
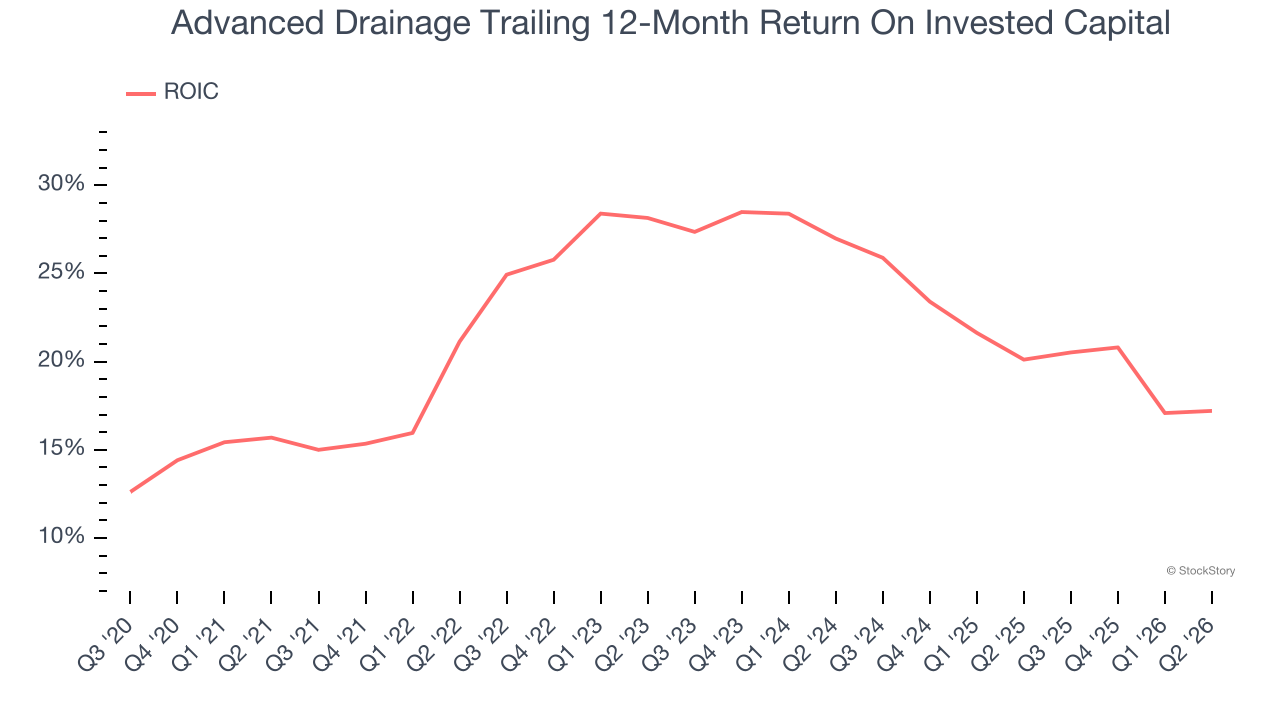
Unfortunately, Advanced Drainage’s ROIC has decreased over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Advanced Drainage isn’t a terrible business, but it doesn’t pass our quality test. After the recent drawdown, the stock trades at 19.8× forward P/E (or $130.85 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at the most dominant software business in the world.
Stocks We Would Buy Instead of Advanced Drainage
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.