

What a time it’s been for Concrete Pumping. In the past six months alone, the company’s stock price has increased by a massive 40.4%, reaching $10.03 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Concrete Pumping, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Concrete Pumping Not Exciting?
We’re happy investors have made money, but we’re sitting this one out for now. Here are three reasons we avoid BBCP, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
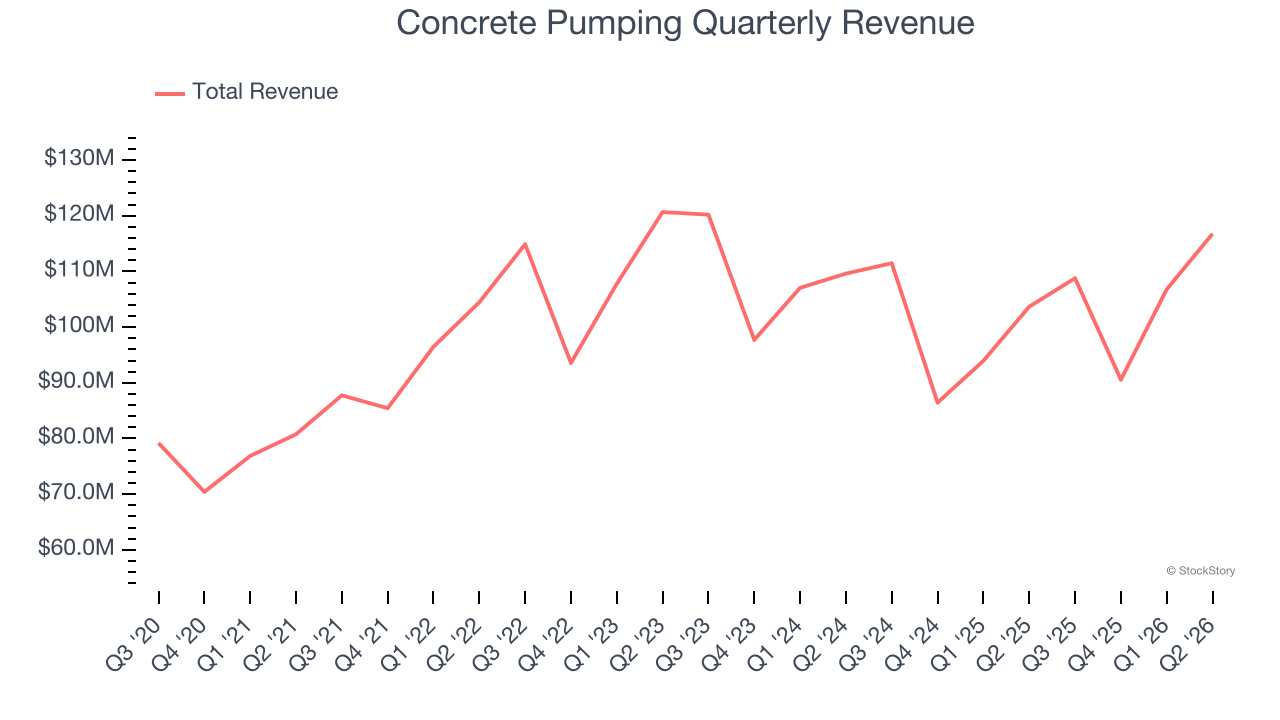
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Regrettably, Concrete Pumping’s sales grew at a mediocre 6.6% compounded annual growth rate over the last five years. This was below our standard for the industrials sector.
2. EPS Took a Dip Over the Last Two Years
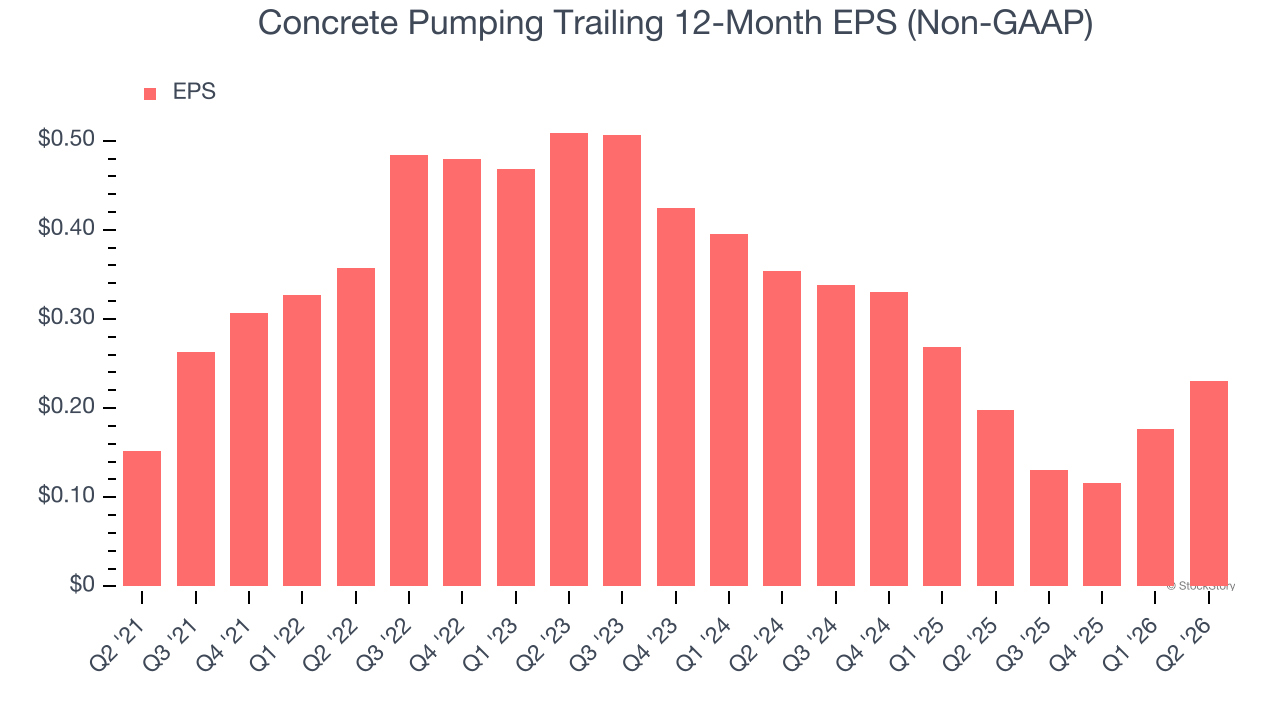
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Sadly for Concrete Pumping, its EPS declined by more than its revenue over the last two years, dropping 19.3%. This tells us the company struggled to adjust to shrinking demand.
3. Previous Growth Initiatives Haven’t Impressed
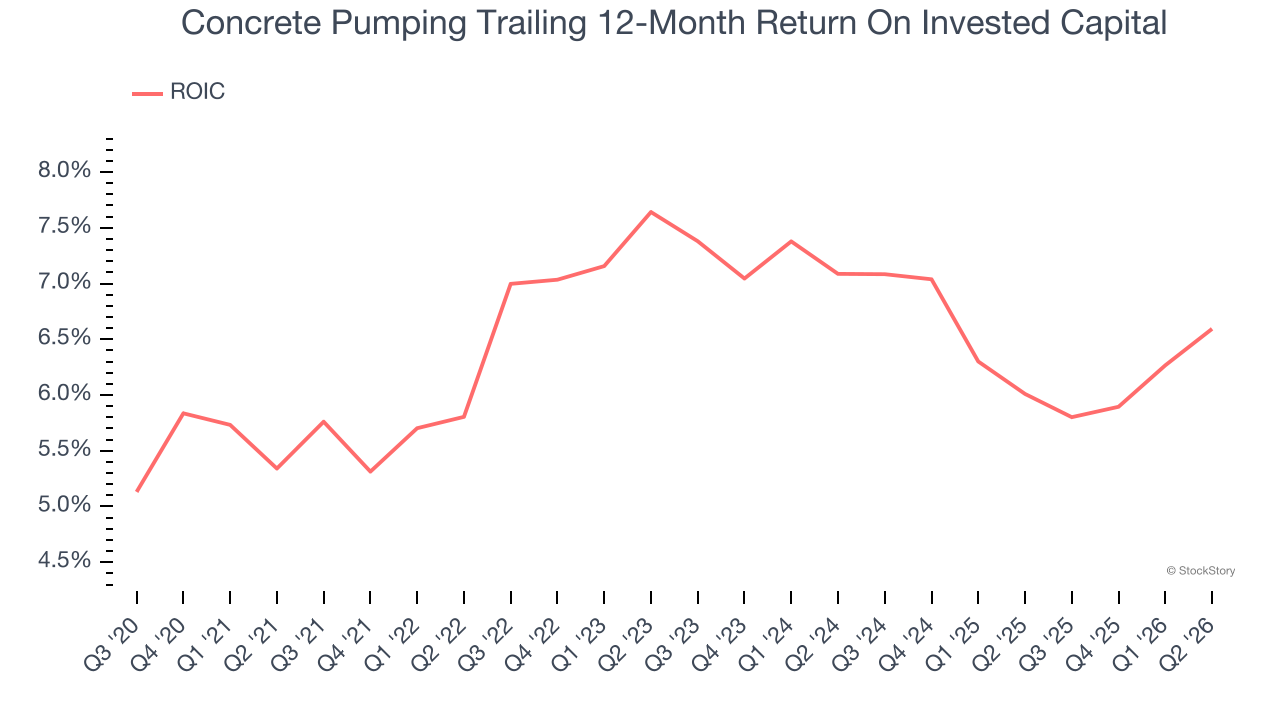
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Concrete Pumping historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 6.6%, somewhat low compared to the best industrials companies that consistently pump out 20%+.
Final Judgment
Concrete Pumping’s business quality ultimately falls short of our standards. Following the recent surge, the stock trades at 33.1× forward P/E (or $10.03 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at the most dominant software business in the world.
Stocks We Like More Than Concrete Pumping
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.